Since April 2026, FOX has been in a holding pattern, floating around $62.59. The stock also fell short of the S&P 500’s 13.5% gain during that period.
Is there a buying opportunity in FOX, or does it present a risk to your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Do We Think FOX Will Underperform?
We’re sitting this one out for now. Here are three reasons why FOXA doesn’t excite us, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
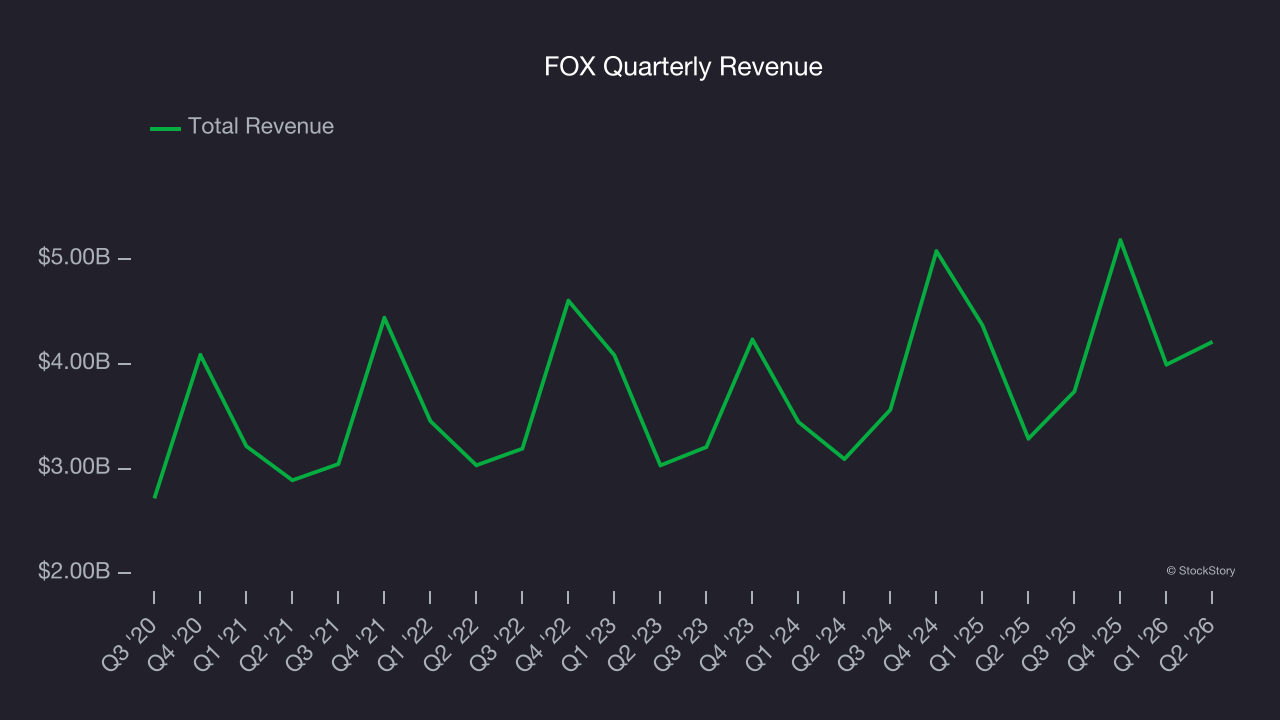
A company’s long-term sales performance can indicate its overall quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Unfortunately, FOX’s 5.8% annualized revenue growth over the last five years was weak. This fell short of our benchmark for the consumer discretionary sector.
2. Mediocre Free Cash Flow Margin Limits Reinvestment Potential
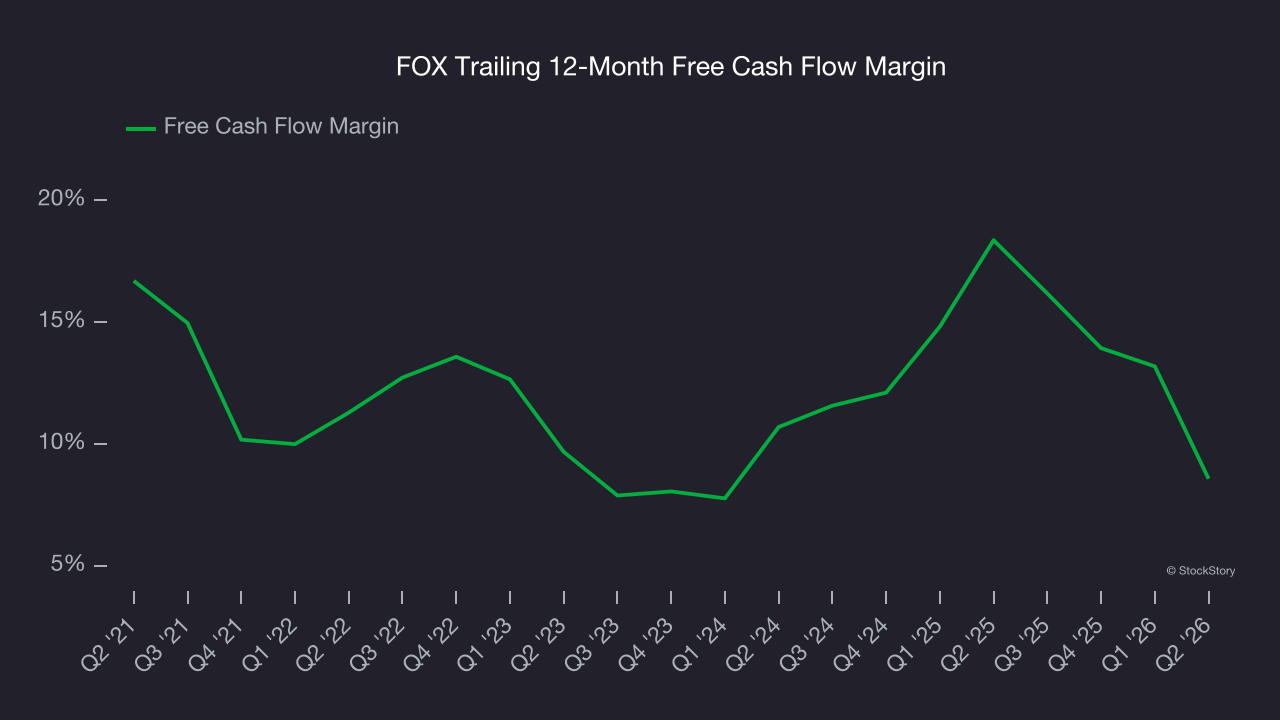
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
FOX has shown poor cash profitability relative to peers over the last two years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 13.3%, below what we’d expect for a consumer discretionary business.
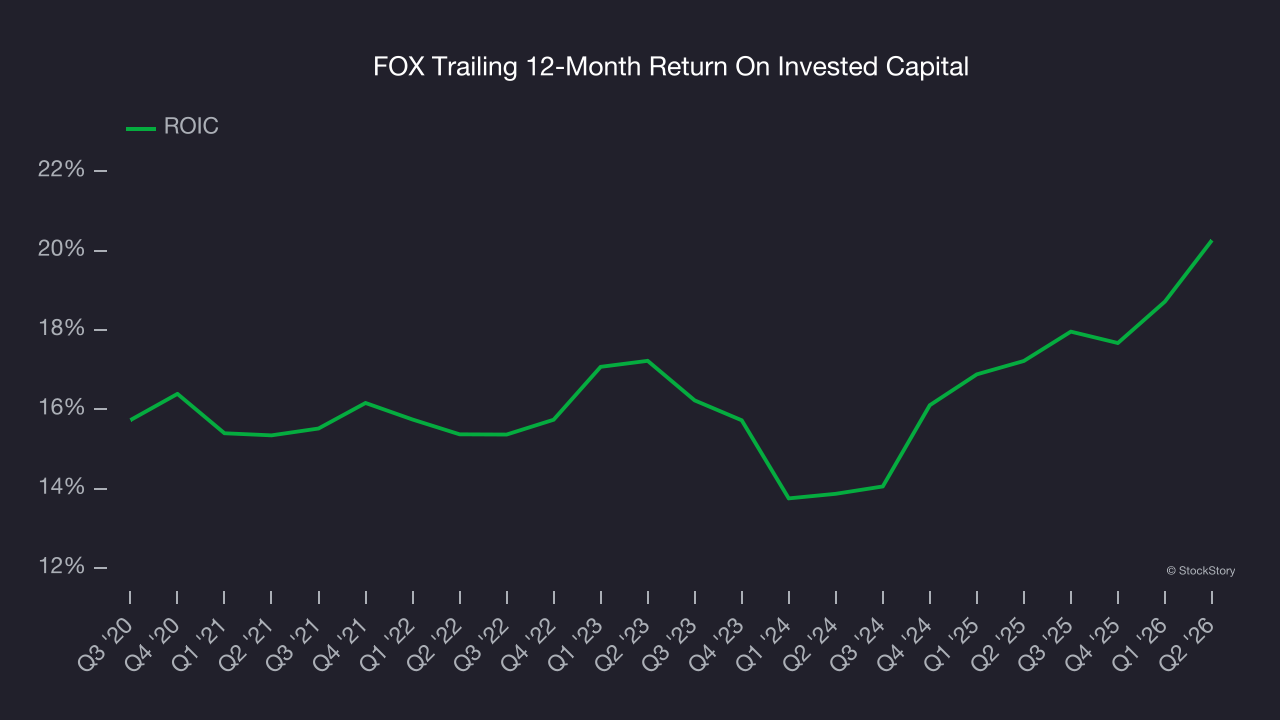
3. New Investments Bear Fruit as ROIC Jumps
A company’s ROIC, or return on invested capital, shows how much operating profit it makes compared to the money it has raised (debt and equity).
On average, FOX’s ROIC increased by 2.4 percentage points annually each year over the last few years. This is a good sign, and we hope the company can continue improving.
Final Judgment
FOX doesn’t pass our quality test. With its shares lagging the market recently, the stock trades at 10.5× forward P/E (or $62.59 per share). This valuation is reasonable, but the company’s shaky fundamentals present too much downside risk. There are superior stocks to buy right now. We’d recommend looking at a fast-growing restaurant franchise with an A+ ranch dressing sauce.
Stocks We Like More Than FOX
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.