Electric vehicle pioneer Tesla (NASDAQ: TSLA) met Wall Street’s revenue expectations in Q3 2026, but sales were flat year on year at $28.05 billion. Its non-GAAP profit of $0.48 per share was 6.3% above analysts’ consensus estimates.
Is now the time to buy Tesla? Find out by accessing our full research report, it’s free.
Tesla (TSLA) Q3 2026 highlights:
- Revenue: $28.05 billion vs analyst estimates of $28.17 billion (in line)
- EPS (non-GAAP): $0.48 vs analyst estimates of $0.45 (6.3% beat)
- Gross Margin: 19.6%, up from 18% in the same quarter last year
- Operating Margin: 2.6%, down from 5.8% in the same quarter last year
- Free Cash Flow Margin: 5.5%, down from 14.2% in the same quarter last year
- Market Capitalization: $1.48 trillion
Revenue growth
Tesla shows that fast growth and massive scale can coexist despite conventional wisdom. The company’s revenue base of $46.85 billion five years ago has more than doubled to $103.6 billion in the last year, translating into an incredible 17.2% annualized growth rate.
Over the same period, Tesla’s automotive peers Rivian, General Motors, and Ford put up annualized growth rates of 70.4%, 7.4%, and 6.8%, respectively. Just note that while Rivian has the most similar vehicles to Tesla, comparisons aren’t exactly apples-to-apples because it’s growing from a much smaller revenue base. 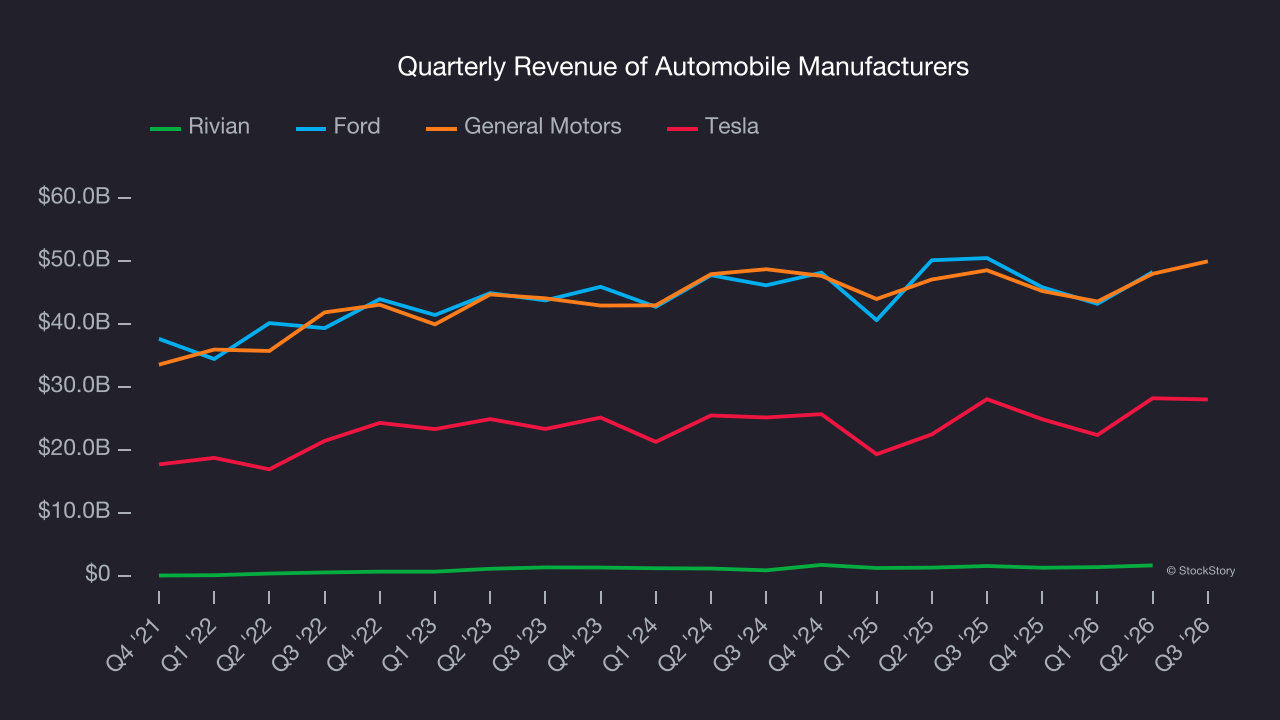
We at StockStory emphasize long-term growth, but for disruptive companies like Tesla, a half-decade historical view may miss emerging trends in autonomous vehicles and energy. Tesla’s recent performance shows its demand has slowed significantly as its annualized revenue growth of 3.3% over the last two years was well below its five-year trend. 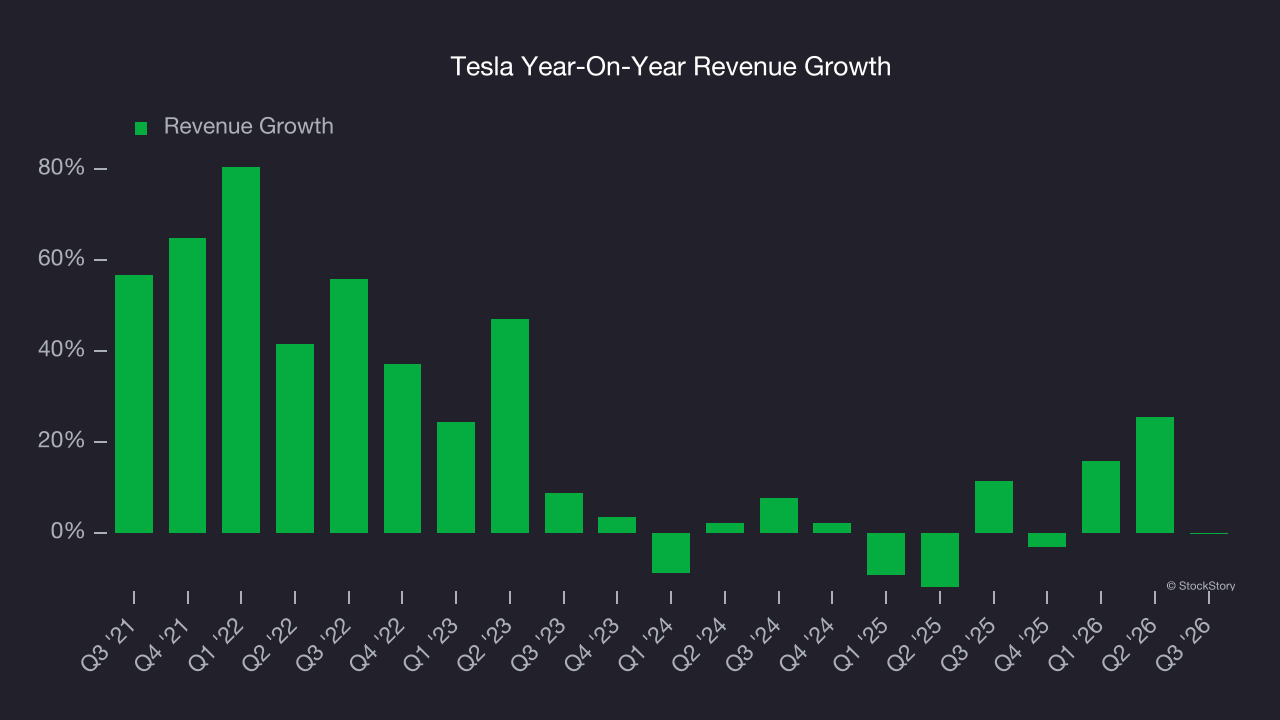
This quarter, Tesla’s $28.05 billion of revenue was flat year on year and in line with Wall Street’s estimates. Looking ahead, sell-side This projection is admirable for a company of its scale and illustrates the market is baking in success for its newer products.
ONE MORE THING: The $21 AI Application Stock Wall Street Forgot. While Wall Street obsesses over who’s building AI, one company is already using it to print money. And nobody’s paying attention.
AI chip stocks trade at ridiculous valuations. This company processes a trillion consumer signals monthly using AI and trades at a third of the price. The gap won’t last. The institutions will figure it out. You need to see this first. Read the FREE Report Before They Notice.
Automotive: act one
Revenue: the race for dominance
Tesla is primarily an automobile manufacturer today and generates 72.4% of its revenue through the sale and leasing of EVs. It historically produced expensive, high-end EVs, but after years of operating losses, has shifted its focus to the mass market with affordable vehicles. The Model 3 and Model Y (released in 2017 and 2019) are the headliners of this story, and we’ll dive into their impacts below.
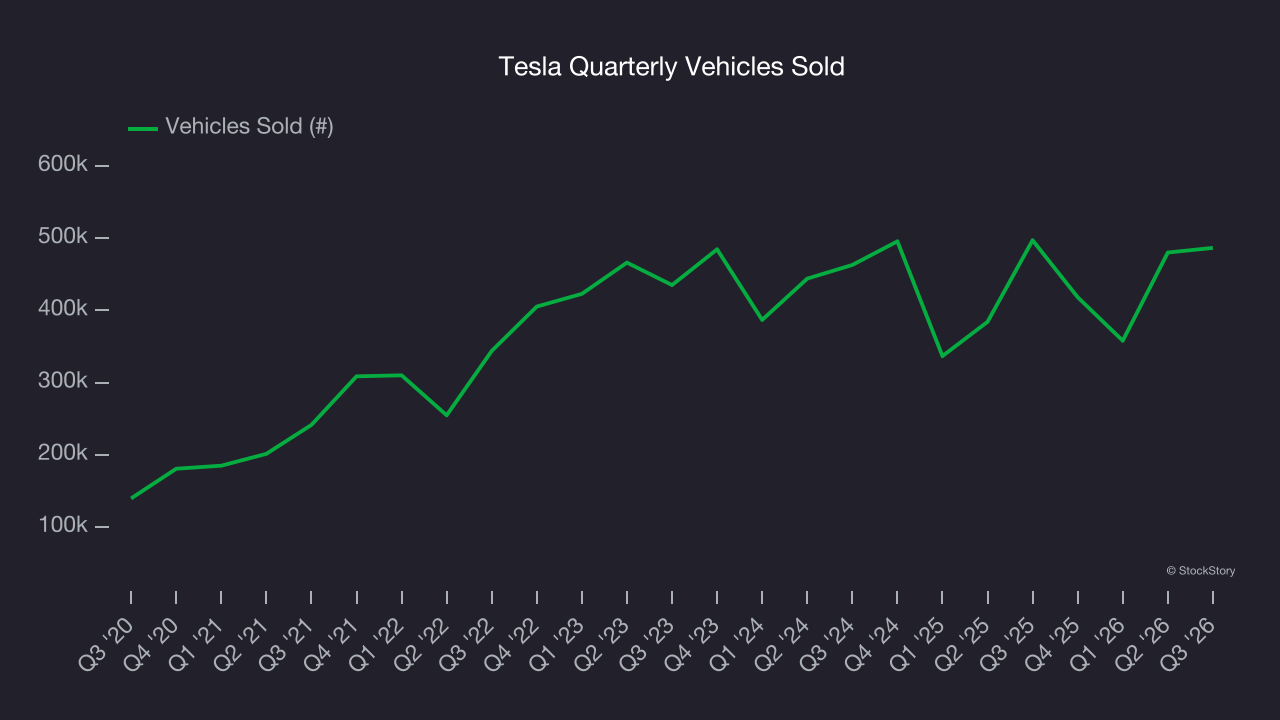
Over the last five years, Tesla’s vehicles sold grew by 16.6% annually to 1.74 million units in the last year. This is in line with its 14.8% annualized growth rate for Automotive revenue, implying that its average vehicle price was stable.
Specifically, Tesla’s average revenue per vehicle sold was $43,033 for the trailing 12 months, about the same as the $46,620 price tag in 2021.
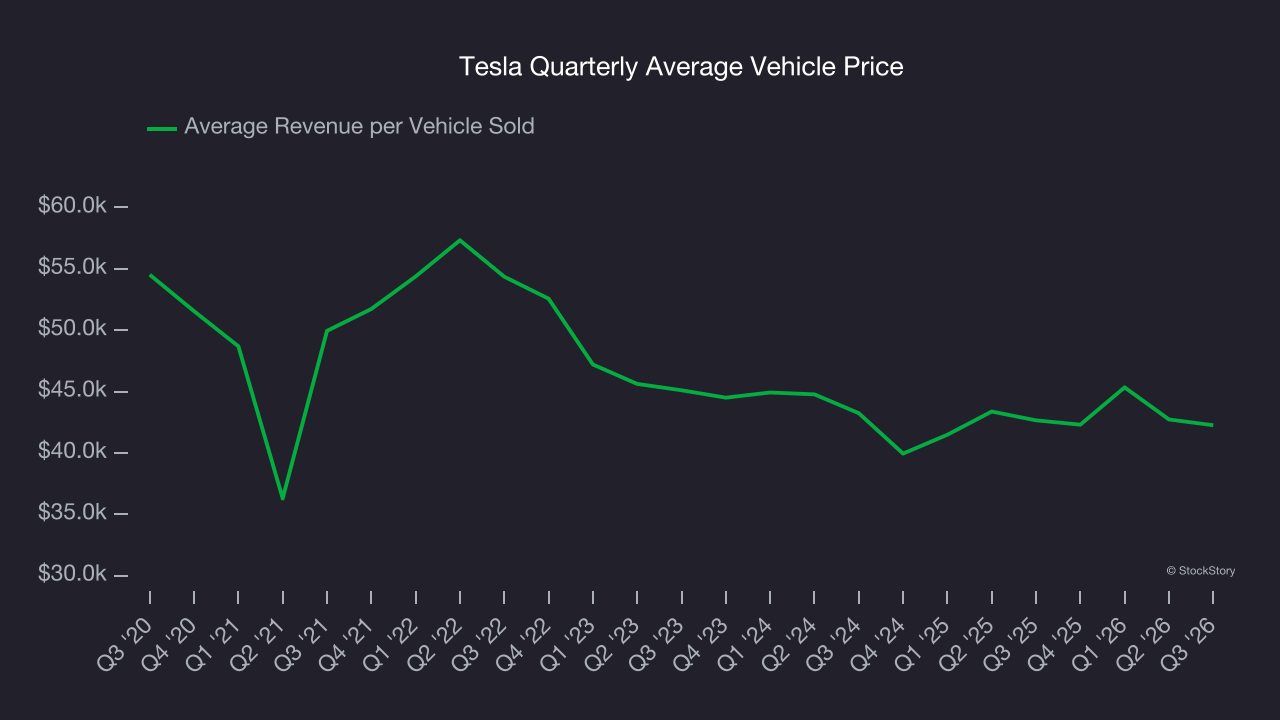
These unit and pricing trends uncover three facets of the company’s automotive business:
1) It has achieved its goal of selling more Model 3 and Model Y vehicles, which carry lower price tags than other models, 2) the scaling production of its mass-market models is boosting manufacturing efficiency because it lowers the fixed cost per vehicle sold, and 3) rather than using the cost-saving benefits to offer cheaper prices, Tesla is retaining the incremental profits.
In Q3, Tesla’s vehicles sold shrank by 2.1% year on year to 486,532 units. Putting this print side-by-side with its 3% Automotive revenue decline suggests an average vehicle price of $42,258, similar to the same quarter last year.
Unit economics: best in class
There’s no denying automobile manufacturing is a tough business. Few upstarts succeed because incumbents like General Motors and Ford can afford to break even on the initial sale of vehicles and instead make money on parts and servicing, which come many years down the line.
Tesla does not disclose the operating profitability of its segments, but we can analyze the gross margins of its various divisions to see how it stacks up. For Automotive, this metric reflects how much revenue is left after paying for the raw materials, components, and direct labor costs that go into manufacturing and producing its vehicles.
Thankfully for investors, Tesla has crossed the chasm as its Automotive segment boasted an average gross margin of 21.1% over the last five years. While it may be low in absolute terms, Tesla’s margin was best in class for the industry and illustrates its superior pricing power and procurement capabilities.
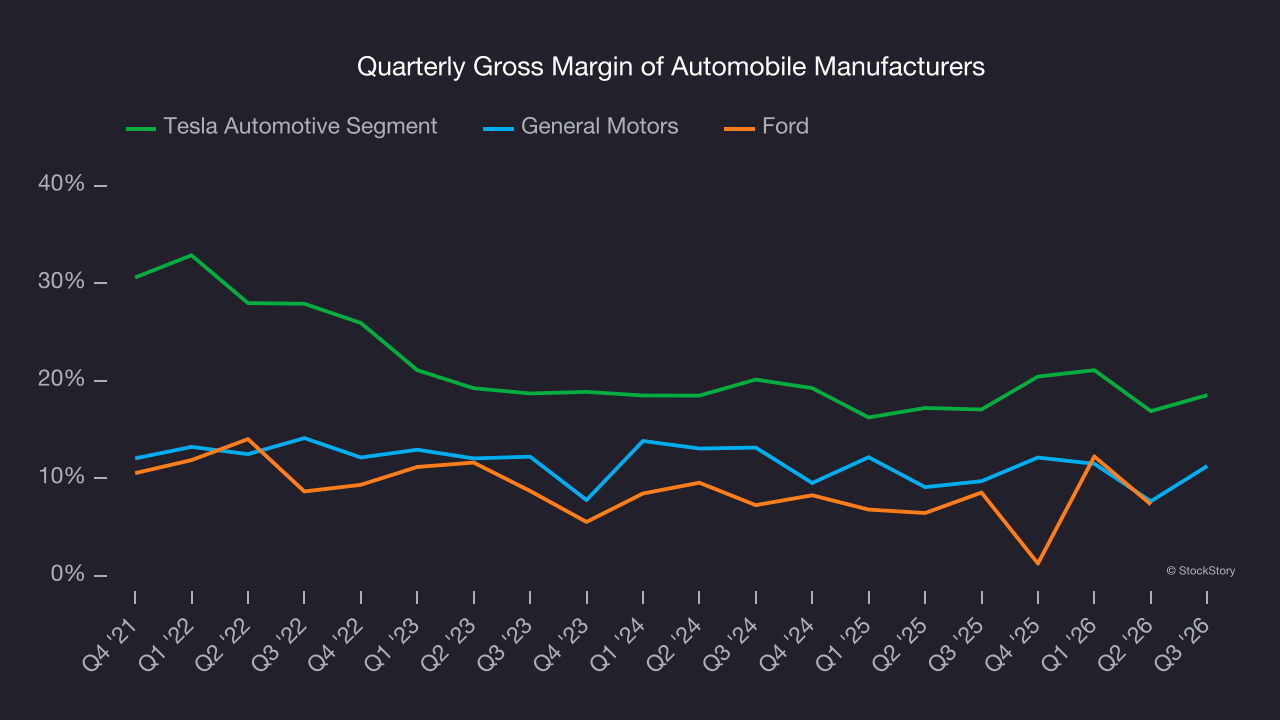
Looking under the hood, Automotive’s annual gross margin fell from 22% five years ago to 19.1% in the last year. Because its average price remained steady, this indicates the company has become less efficient at sourcing parts and assembling cars. The trend slightly improved this quarter as its gross margin stabilized, but we wouldn’t put too much weight on short-term results.
Key takeaways from Tesla’s Q3 results
It was good to see Tesla beat analysts’ EPS expectations this quarter. On the other hand, its revenue was in line. Overall, this was a mixed quarter. The stock remained flat at $384.98 immediately after reporting.
Should you buy the stock or not? What happened in the latest quarter matters, but not as much as longer-term business quality and valuation, when deciding whether to invest in this stock. We cover that in our actionable full research report which you can read here (it’s free).