Boat and marine products retailer MarineMax (NYSE: HZO) missed Wall Street’s revenue expectations in calendar Q3 2026 (fiscal Q4 2026), with revenue falling 5.8% year on year to $520.1 million. Its non-GAAP loss of $0.08 per share was significantly below analysts’ consensus estimates.
For more on MarineMax, read our free full research report.
MarineMax (HZO) Q3 CY2026 highlights:
- Revenue $520.1 million vs S&P analysts’ consensus estimates of $544.1 million (5.8% year-on-year decline, 4.4% miss)
- Adjusted EPS -$0.08 vs S&P analysts’ consensus estimates of $0.05 (significant miss)
- Adjusted EBITDA $21.82 million vs analysts’ consensus estimates of $26.51 million (4.2% margin, 17.7% miss)
- Operating margin -0.3%, down from 2.5% in the same quarter last year
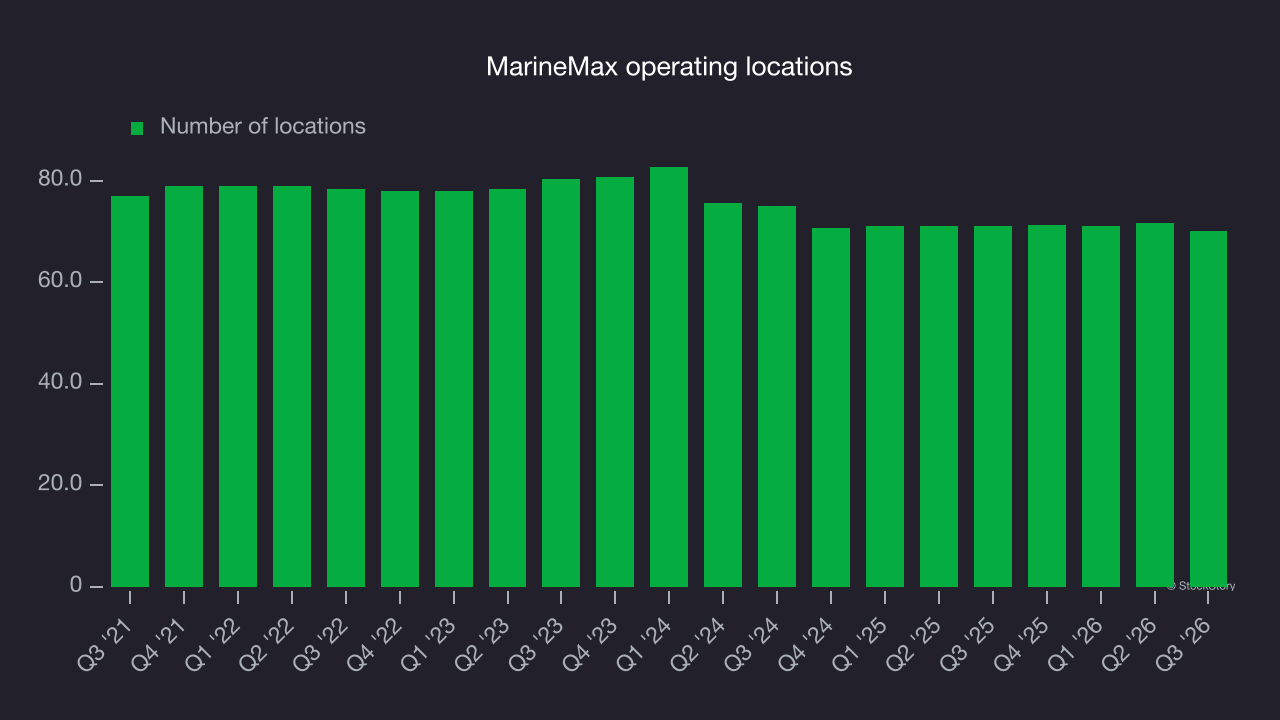
- Locations 70 at quarter end, down from 71 in the same quarter last year
- Same-store sales fell 5.7% year on year (2.3% in the same quarter last year)
- Market capitalization $1.16 billion
“Fiscal 2026 demonstrated the strength of MarineMax's diversified business model and the benefits of our strategic investments to broaden our marine offerings and expand our presence in durable, higher-margin businesses,” said Brett McGill, the Company’s Chief Executive Officer and President. “Despite a challenging retail environment, contributions from across our portfolio helped offset market pressures, underscoring the value of our diversification strategy. Since 2019, we have expanded our higher-margin, non-boat revenue streams, contributing to a significant improvement in gross margin from 26.1% in fiscal 2019 to 34.9% in fiscal 2026. I want to thank our team members, whose continued dedication and commitment to our customers have made these results possible.
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can deliver a good quarter or two, but the best consistently grow over the long term.
With $2.16 billion in revenue over the past 12 months, MarineMax is a small retailer, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and negotiating leverage with suppliers.
MarineMax’s demand was weak over the last three years. Its revenue fell by 3.3% annually as it closed stores and saw lower revenue at existing, established locations.
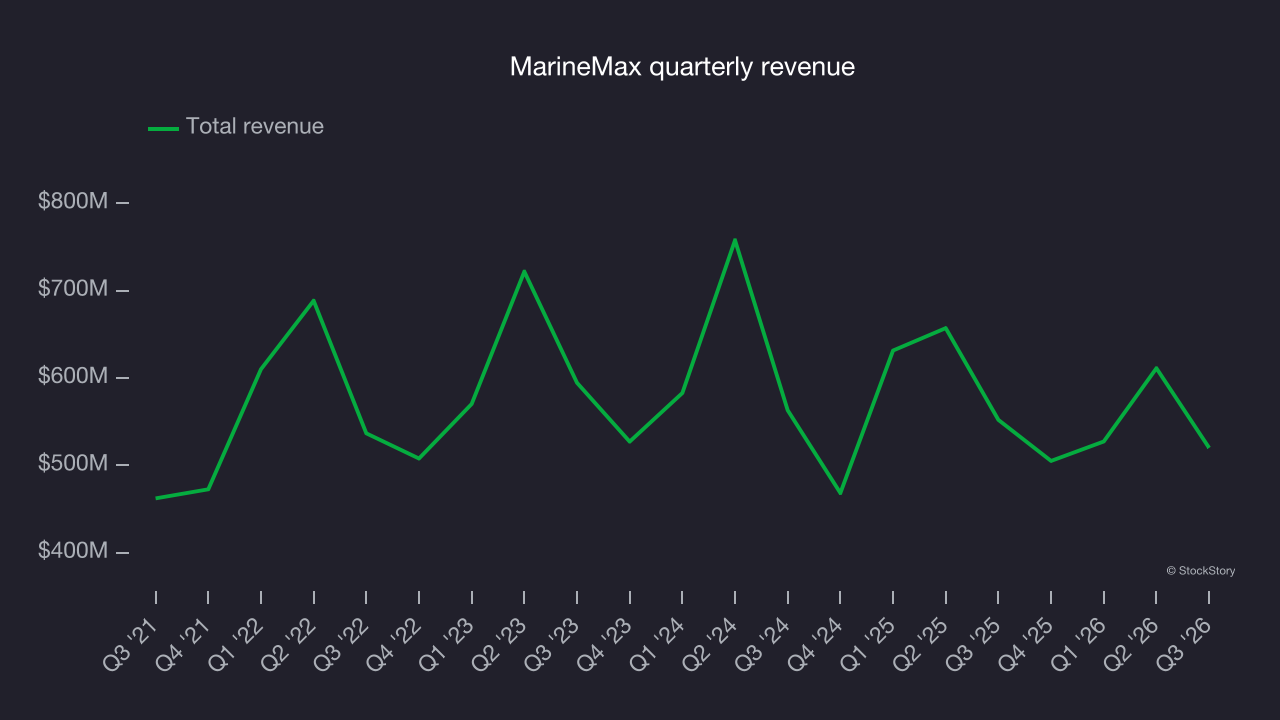
This quarter, MarineMax missed Wall Street’s consensus estimates and reported an uninspiring 5.8% year-on-year revenue decline, generating $520.1 million in revenue.
Looking ahead, sell-side analysts expect revenue to grow 5.7% over the next 12 months, according to S&P, an acceleration versus the last three years. This projection is healthy and suggests its newer products will drive stronger revenue growth.
Store performance
Number of stores
MarineMax listed 70 locations in the latest quarter and has reduced its store count over the last two years, averaging 4.7% annual declines.
When a retailer shutters stores, it usually means that brick-and-mortar demand is less than supply, and it is responding by closing underperforming locations to improve profitability.
Same-store sales
The change in a company’s store base only tells one side of the story. The other is the performance of its existing locations and e-commerce sales, which informs management teams whether they should expand or downsize their physical footprints. Same-store sales provide insight into this performance because the metric measures organic growth for a retailer’s e-commerce platform and brick-and-mortar shops that have existed for at least a year.
MarineMax’s demand has been shrinking over the last two years as its same-store sales have averaged 3.1% annual declines. This performance isn’t ideal, and MarineMax is attempting to boost same-store sales by closing stores (fewer locations sometimes lead to higher same-store sales).
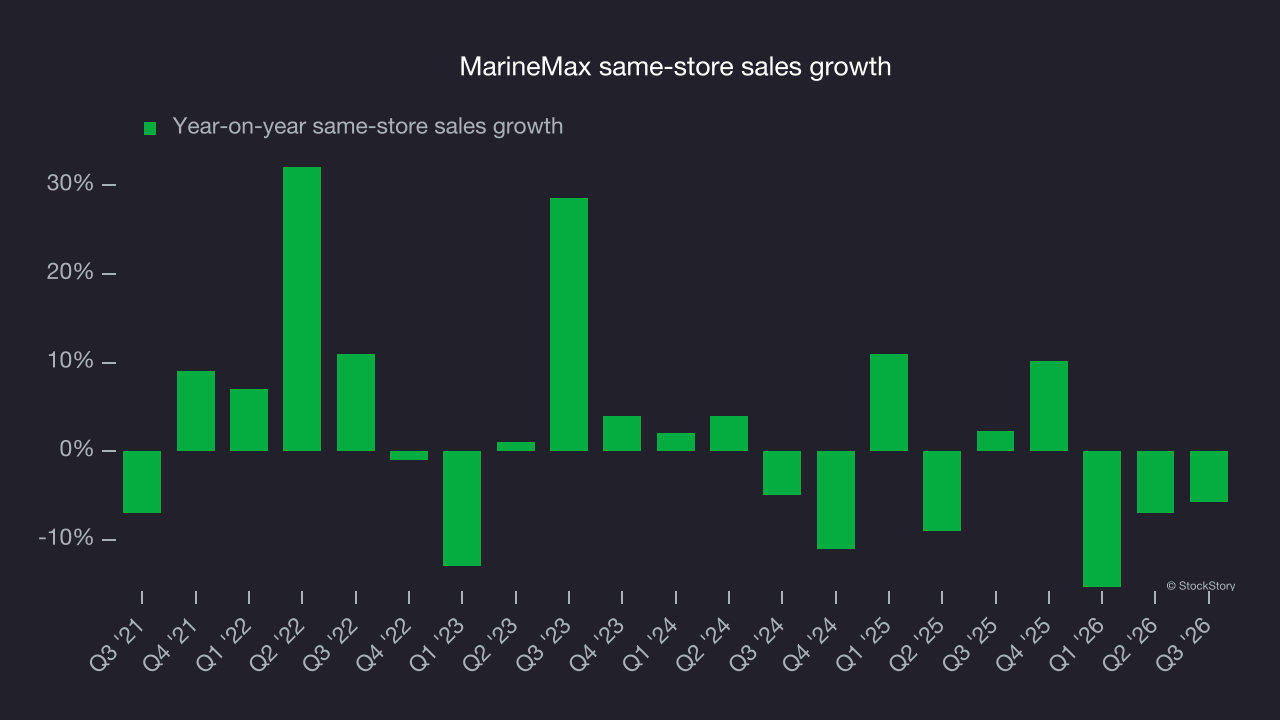
In the latest quarter, MarineMax’s same-store sales fell by 5.7% year on year. This decrease represents a further deceleration from its historical levels.
Key takeaways from MarineMax’s Q3 results
MarineMax’s quarter could have been better, despite gross margin coming in well above analysts’ consensus estimates. Revenue and EBITDA both fell short of Wall Street’s consensus estimates. Shares remained flat at $52.69 immediately after the release.
Assessing MarineMax at its current price means considering its valuation, business quality and latest quarterly results. For more, read the full research report here (it’s free).