Midstream energy infrastructure company Genesis Energy (NYSE: GEL) reported revenue ahead of Wall Street’s expectations in Q3 2026, with revenue up 8.5% year on year to $449.3 million. Its GAAP loss of $0.05 per share was 72.2% above analysts’ consensus estimates.
For more on Genesis Energy, read our free full research report.
Genesis Energy (GEL) Q3 2026 highlights:
- Revenue $449.3 million vs S&P analysts’ consensus estimates of $407.4 million (8.5% year-on-year growth, 10.3% beat)
- EPS (GAAP) -$0.05 vs analysts’ consensus estimates of -$0.18 (72.2% beat)
- Adjusted EBITDA $130.5 million vs analysts’ consensus estimates of $126.4 million (29% margin, 3.2% beat)
- Operating margin 15.4%, down from 19% in the same quarter last year
- Market capitalization $1.62 billion
Revenue growth
A company’s long-term performance can give signals about its business quality. Even a bad business, especially in a cyclical industry, can perform well for a year or so, but a top-tier one should exhibit resilience through cycles. Over the last five years, Genesis Energy’s demand was weak and its revenue declined by 1.3% per year. This fell short of our standards and suggests poor business quality.
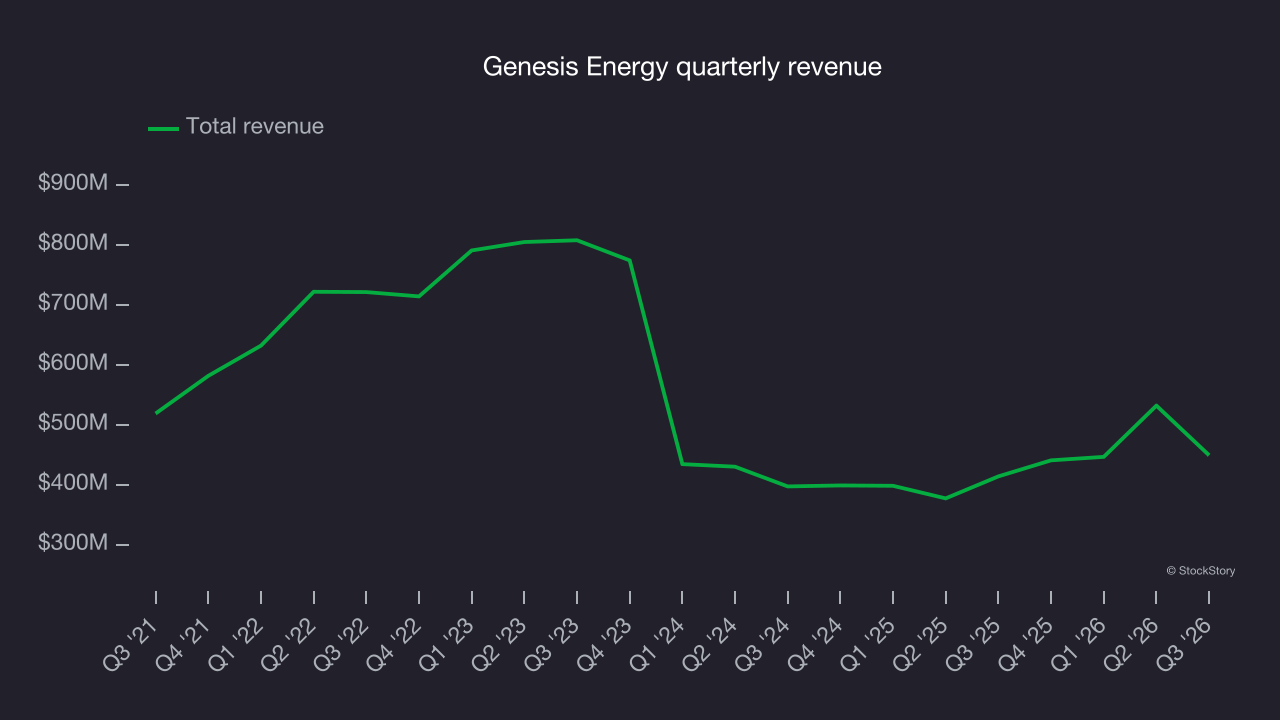
Energy cycles can be long enough that a single five-year period can still reflect one price environment, which is why an additional, decade-long view can help capture through-cycle performance. Genesis Energy’s annualized revenue growth of 0.5% over the last ten years is above its five-year trend, suggesting some bright spots.
This quarter, Genesis Energy reported year-on-year revenue growth of 8.5%, and its $449.3 million of revenue exceeded Wall Street’s consensus estimates by 10.3%.
Adjusted EBITDA margin
Adjusted EBITDA margin strips out accounting distortions tied to depletion and historical drilling spend, providing a clearer view of the cash-generating power of the underlying asset base before financing and reinvestment decisions.
Genesis Energy was profitable over the last five years but held back by its large cost base. Its average EBITDA margin of 28.5% was weak for an upstream and integrated energy business.
On the positive side, Genesis Energy’s EBITDA margin rose by 6.6 percentage points over the last year.
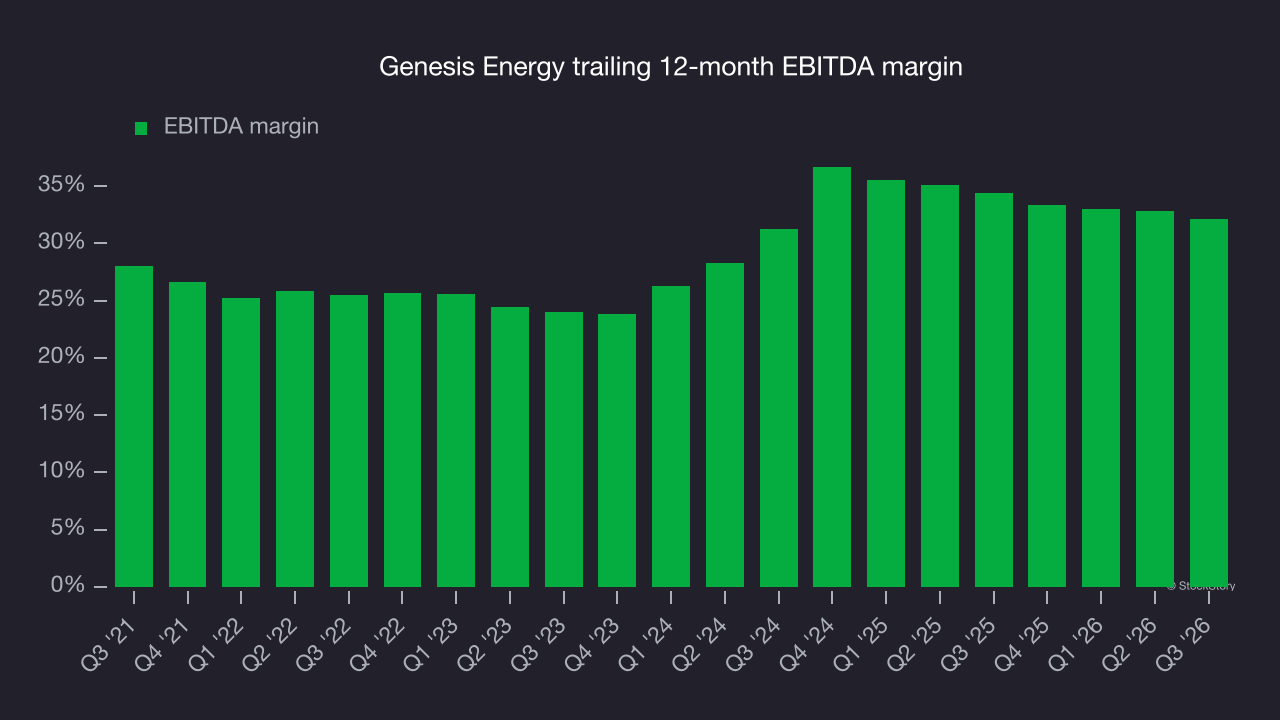
This quarter, Genesis Energy generated an EBITDA margin of 29%, down 2.8 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue. Adjusted EBITDA beat Wall Street’s consensus estimates by 3.2%.
Free cash flow
As mentioned above, adjusted EBITDA ignores capital structure and drilling expenditure decisions. These are two major aspects of an energy producer’s business, so investors need to account for them to get a comprehensive picture of business quality. In other words, adjusted EBITDA margins could be solid but free cash flow poor because the asset’s decline rates are high and drilling is expensive. Free cash flow tells you not only about the economics of past production but also how much it costs to stay in business through further drilling or extraction.
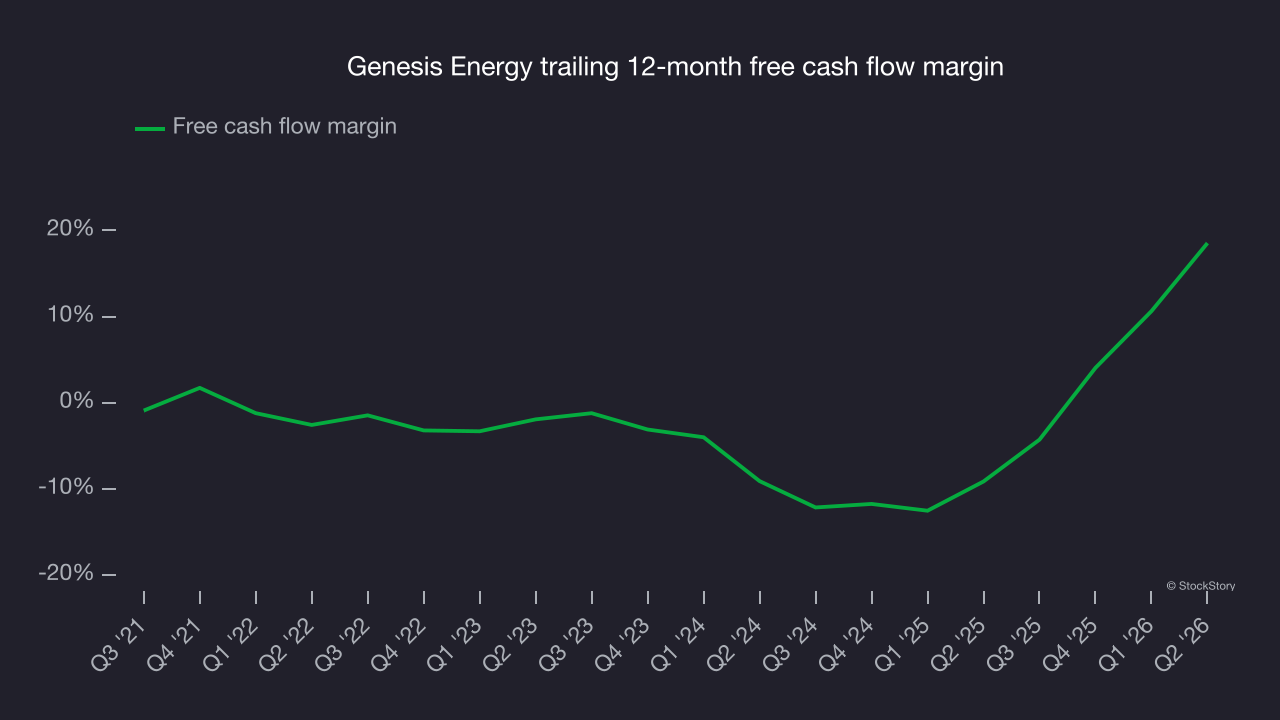
Genesis Energy broke even from a free cash flow perspective over the last five years, giving the company limited opportunities to return capital to shareholders.
While the level of free cash flow margins is important, their consistency matters just as much.
Genesis Energy’s ratio of quarterly free cash flow volatility to West Texas Intermediate, or WTI, crude price volatility over the past five years was 79.9 (lower is better), indicating that its cash generation is far more sensitive to commodity-price swings than most peers. This elevated volatility limits its access to capital in downturns and makes it unlikely to act as a consolidator when weaker competitors come under pressure.
Why assess stability against commodity prices at the free cash flow line? Why not compare revenue or EBITDA to WTI in the case of Genesis Energy? What ultimately matters is not how much revenue or profit a company earns when prices are high but how much cash it can generate when prices are low. Free cash flow is the superior metric because it includes everything from hedging effectiveness to growth and maintenance capex to management behavior during good times and bad.
Key takeaways from Genesis Energy’s Q3 results
Genesis Energy delivered a solid Q3, with revenue well above Wall Street’s consensus estimates and EPS also topping expectations. Those beats were key positives for the quarter. Shares remained flat at $13.33 immediately after the results.
Before investing in Genesis Energy, consider the bigger picture of valuation, business quality and the latest earnings. Read the full research report here (it’s free).