Quarterly earnings results are a good time to check in on a company’s progress, especially compared to its peers in the same sector. Today we are looking at O'Reilly (NASDAQ: ORLY) and the best and worst performers in the auto parts retailer industry.
Cars are complex machines that need maintenance and occasional repairs, and auto parts retailers cater to the professional mechanic as well as the do-it-yourself (DIY) fixer. Work on cars may entail replacing fluids, parts, or accessories, and these stores have the parts and accessories for these jobs. While e-commerce competition presents a risk, these stores have a leg up due to the combination of broad and deep selection as well as expertise provided by sales associates. Another change on the horizon could be the increasing penetration of electric vehicles.
The 5 auto parts retailer stocks we track reported a softer Q3. As a group, revenues were in line with analysts’ consensus estimates.
While some auto parts retailer stocks have fared somewhat better than others, they have collectively declined. On average, share prices are down 4.9% since the latest earnings results.
Best Q3: O'Reilly (NASDAQ: ORLY)
Serving both the DIY customer and professional mechanic, O’Reilly Automotive (NASDAQ: ORLY) is an auto parts and accessories retailer that sells everything from fuel pumps to car air fresheners to mufflers.
O'Reilly reported revenues of $5.12 billion, up 8.8% year on year. This print exceeded analysts’ expectations by 2.1%. Overall, it was a satisfactory quarter for the company with a beat of analysts’ EPS estimates but a slight miss of analysts’ gross margin estimates.
Brad Beckham, O’Reilly’s CEO, commented, “I would like to thank our Team Members for their unwavering commitment to providing industry-leading service to each of our customers. Team O’Reilly’s dedication was evident in our strong third quarter comparable store sales increase of 7.2%. This robust growth came on top of strong sales in the third quarter last year, resulting in a two-year stack of 12.8%, and was driven by share gains on both sides of our business, with double-digit growth in our professional business and mid-single digit growth in DIY. Our impressive top-line growth, coupled with a $39 million benefit from tariff refunds received during the third quarter, drove a 14% increase in our third quarter diluted earnings per share. We are extremely pleased with the continued ability of our Team to deliver industry-leading results through their hard work and unrelenting focus on our customers.”
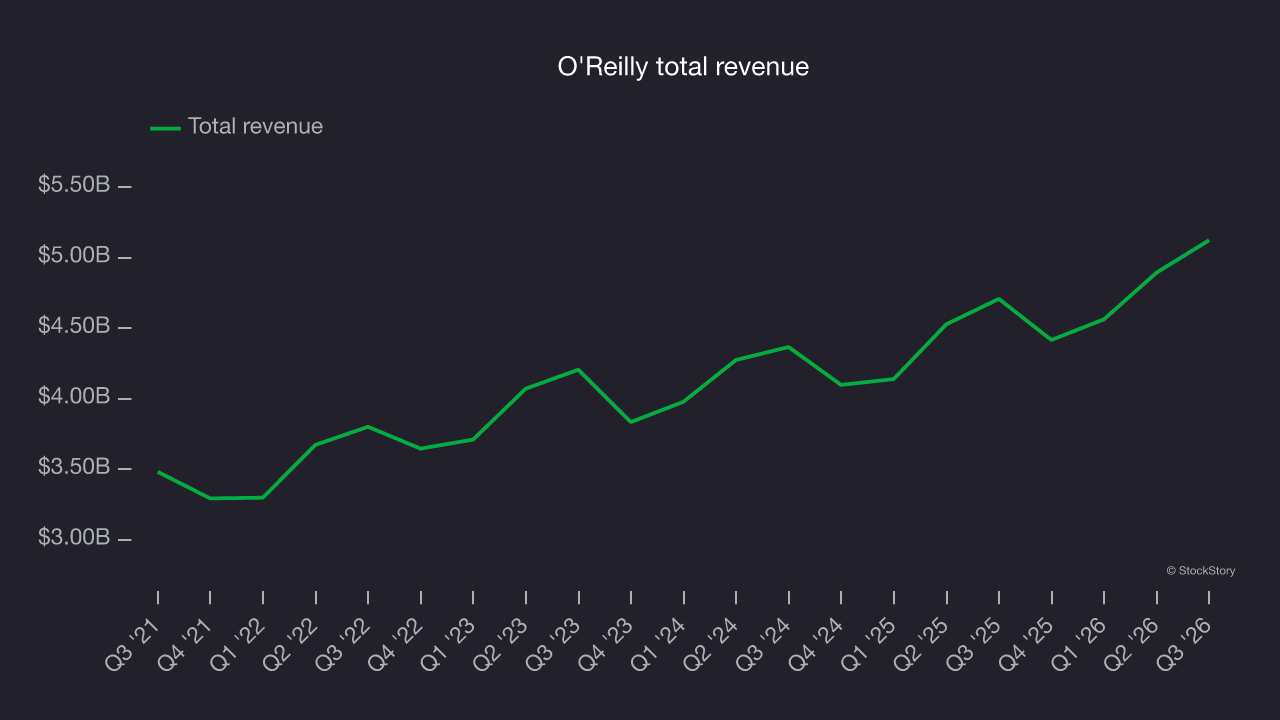
O'Reilly scored the biggest analyst estimate beat, fastest revenue growth, and highest full-year guidance raise among its peers. The results were likely priced in, however, and the stock is flat since reporting. It currently trades at $90.37.
Is now the time to buy O'Reilly? Access our full analysis of the earnings results here, it’s free.
Genuine Parts (NYSE: GPC)
Largely targeting the professional customer, Genuine Parts (NYSE: GPC) sells auto and industrial parts such as batteries, belts, bearings, and machine fluids.
Genuine Parts reported revenues of $6.52 billion, up 4.2% year on year, in line with analysts’ expectations. The business performed better than its peers, but it was unfortunately a mixed quarter with a narrow beat of analysts’ gross margin estimates but full-year EPS guidance slightly missing analysts’ expectations.
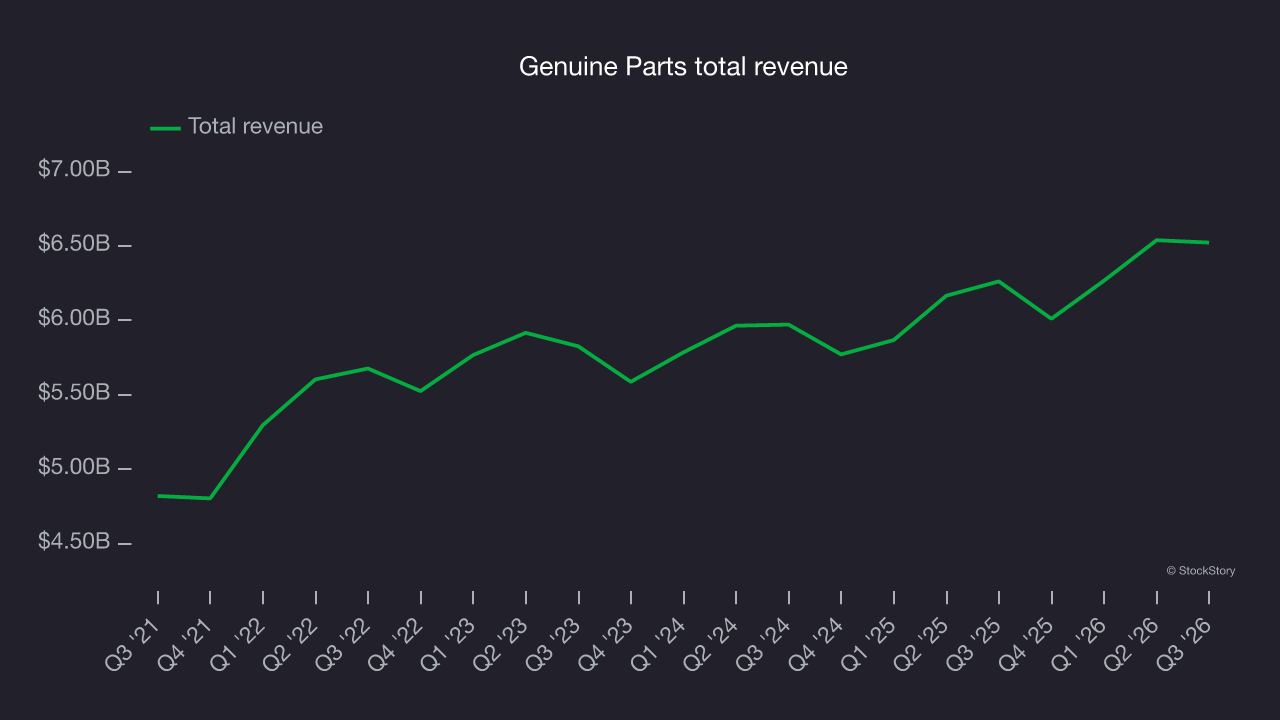
Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 5.6% since reporting. It currently trades at $122.87.
Is now the time to buy Genuine Parts? Access our full analysis of the earnings results here, it’s free.
Weakest Q3: Monro (NASDAQ: MNRO)
Started as a single location in Rochester, New York, Monro (NASDAQ: MNRO) provides common auto services such as brake repairs, tire replacements, and oil changes.
Monro reported revenues of $283.6 million, down 1.8% year on year, in line with analysts’ expectations. It was a sluggish quarter as it posted a significant miss of analysts’ EPS estimates and a slight miss of analysts’ gross margin estimates.
Monro delivered the slowest revenue growth in the group. As expected, the stock is down 23.2% since the results and currently trades at $10.99.
Read our full analysis of Monro’s results here.
Advance Auto Parts (NYSE: AAP)
Founded in Virginia in 1932, Advance Auto Parts (NYSE: AAP) is an auto parts and accessories retailer that sells everything from carburetors to motor oil to car floor mats.
Advance Auto Parts reported revenues of $2.01 billion, down 1.2% year on year. This print missed analysts’ expectations by 1.4%. Overall, it was a softer quarter as it also produced full-year EPS guidance slightly missing analysts’ expectations and gross margin in line with analysts’ estimates.
Advance Auto Parts had the weakest full-year guidance update of the whole group. The stock is down 10.1% since reporting and currently trades at $45.60.
Read our full, actionable report on Advance Auto Parts here, it’s free.
AutoZone (NYSE: AZO)
Aiming to be a one-stop shop for the DIY customer, AutoZone (NYSE: AZO) is an auto parts and accessories retailer that sells everything from car batteries to windshield wiper fluid to brake pads.
AutoZone reported revenues of $6.59 billion, up 5.6% year on year. This result lagged analysts’ expectations by 1.6%. It was a softer quarter as it also logged a slight miss of analysts’ gross margin estimates.
AutoZone had the weakest performance against analyst estimates among its peers. The stock is up 14.7% since reporting and currently trades at $3,216.
Read our full, actionable report on AutoZone here, it’s free.
Market update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Top 5 Quality Compounder Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.