Over the last six months, Supernus Pharmaceuticals’s shares have sunk to $41.99, producing a disappointing 14.7% loss - a stark contrast to the S&P 500’s 16.4% gain. This may have investors wondering how to approach the situation.
Is there a buying opportunity in Supernus Pharmaceuticals, or does it present a risk to your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Do We Think Supernus Pharmaceuticals Will Underperform?
Despite the more favorable entry price, we’re sitting this one out for now. Here are three reasons you should be careful with SUPN, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
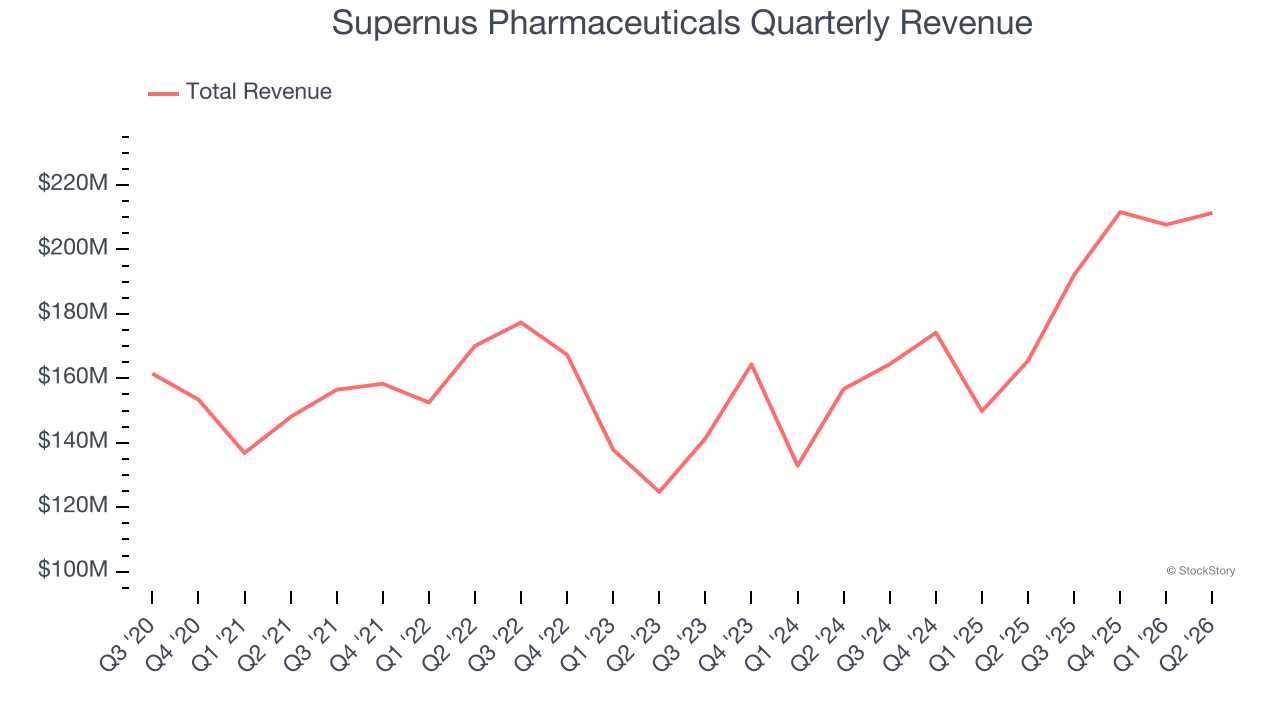
A company’s long-term sales performance is one signal of its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Over the last five years, Supernus Pharmaceuticals grew its sales at a mediocre 6.5% compounded annual growth rate. This was below our standard for the healthcare sector.
2. Fewer Distribution Channels Limit Its Ceiling
Larger companies benefit from economies of scale, where fixed costs like infrastructure, technology, and administration are spread over a higher volume of goods or services, reducing the cost per unit. Scale can also lead to bargaining power with suppliers, greater brand recognition, and more investment firepower. A virtuous cycle can ensue if a scaled company plays its cards right.
With just $822.8 million in revenue over the past 12 months, Supernus Pharmaceuticals is a small company in an industry where scale matters. This makes it difficult to build trust with customers because healthcare is heavily regulated, complex, and resource-intensive.
3. Free Cash Flow Margin Dropping
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
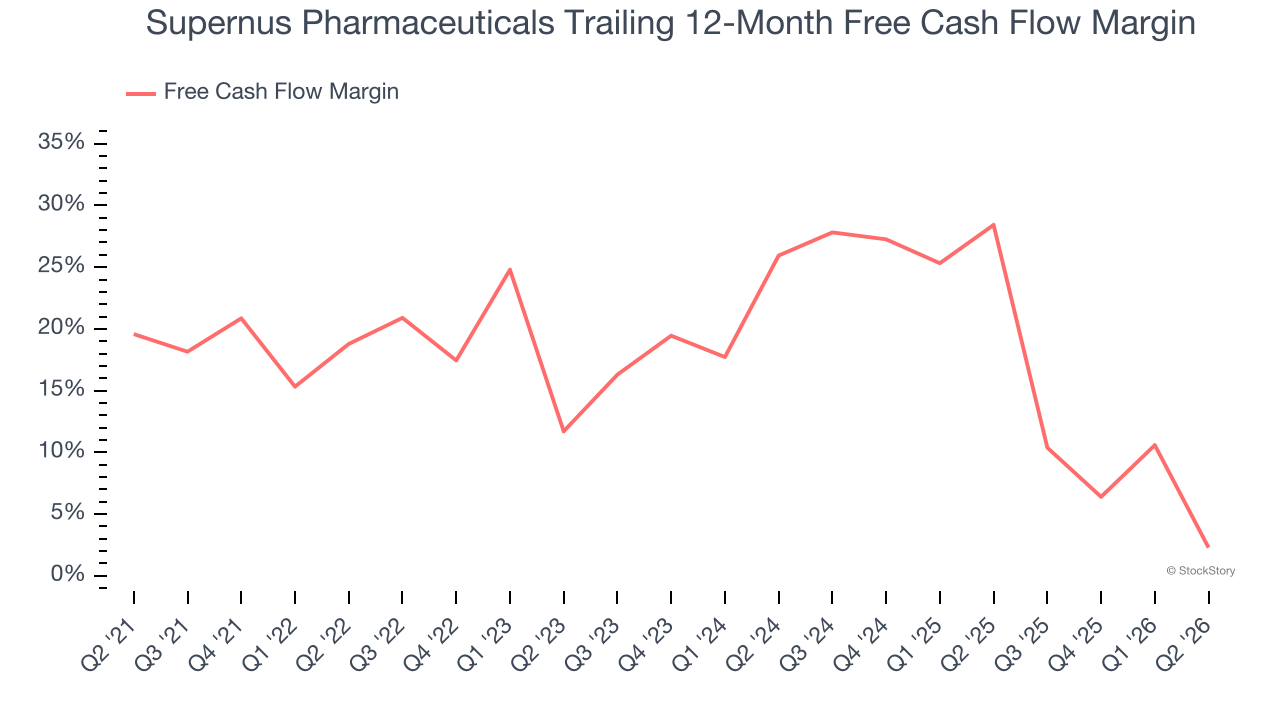
As you can see below, Supernus Pharmaceuticals’s margin dropped by 16.5 percentage points over the last five years. If its declines continue, it could signal increasing investment needs and capital intensity. Supernus Pharmaceuticals’s free cash flow margin for the trailing 12 months was 2.3%.
Final Judgment
We see the value of companies making people healthier, but in the case of Supernus Pharmaceuticals, we’re out. After the recent drawdown, the stock trades at $41.99 per share (or a forward price-to-sales ratio of 2.7×). The market typically values companies like Supernus Pharmaceuticals based on their anticipated profits for the next 12 months, but there aren’t enough published estimates to arrive at a reliable number. You should avoid this stock for now - better opportunities lie elsewhere. We’d suggest looking at the Amazon and PayPal of Latin America.
Stocks We Would Buy Instead of Supernus Pharmaceuticals
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.