The past six months have been a windfall for LifeStance Health Group’s shareholders. The company’s stock price has jumped 92.6%, hitting $12.58 per share. This was partly thanks to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is there a buying opportunity in LifeStance Health Group, or does it present a risk to your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Is LifeStance Health Group Not Exciting?
Despite the momentum, we’re passing on LifeStance Health Group for now. Here are three reasons you should be careful with LFST, plus one stock we’d rather own.
1. Fewer Distribution Channels Limit Its Ceiling
Larger companies benefit from economies of scale, where fixed costs like infrastructure, technology, and administration are spread over a higher volume of goods or services, reducing the cost per unit. Scale can also lead to bargaining power with suppliers, greater brand recognition, and more investment firepower. A virtuous cycle can ensue if a scaled company plays its cards right.
With just $1.58 billion in revenue over the past 12 months, LifeStance Health Group is a small company in an industry where scale matters. This makes it difficult to build trust with customers because healthcare is heavily regulated, complex, and resource-intensive.
2. Mediocre Free Cash Flow Margin Limits Reinvestment Potential
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
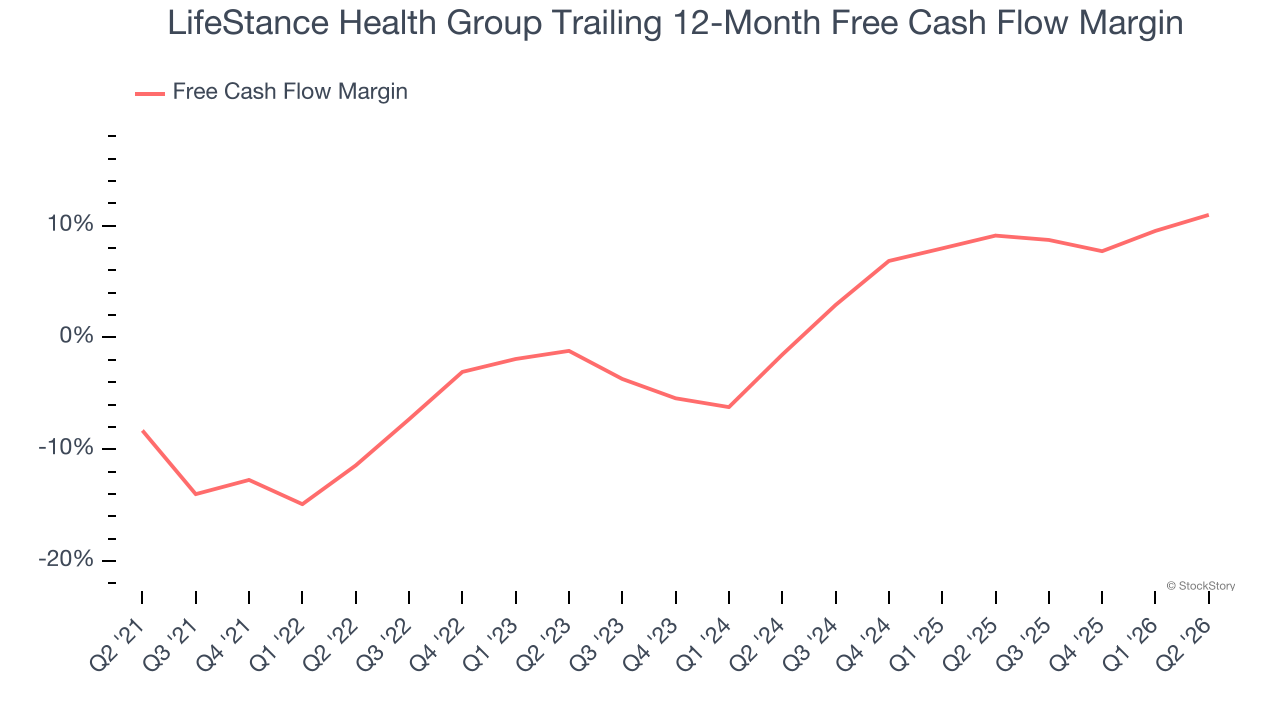
LifeStance Health Group has shown mediocre cash profitability relative to peers over the last five years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 3%, below what we’d expect for a healthcare business.
3. Previous Growth Initiatives Have Lost Money
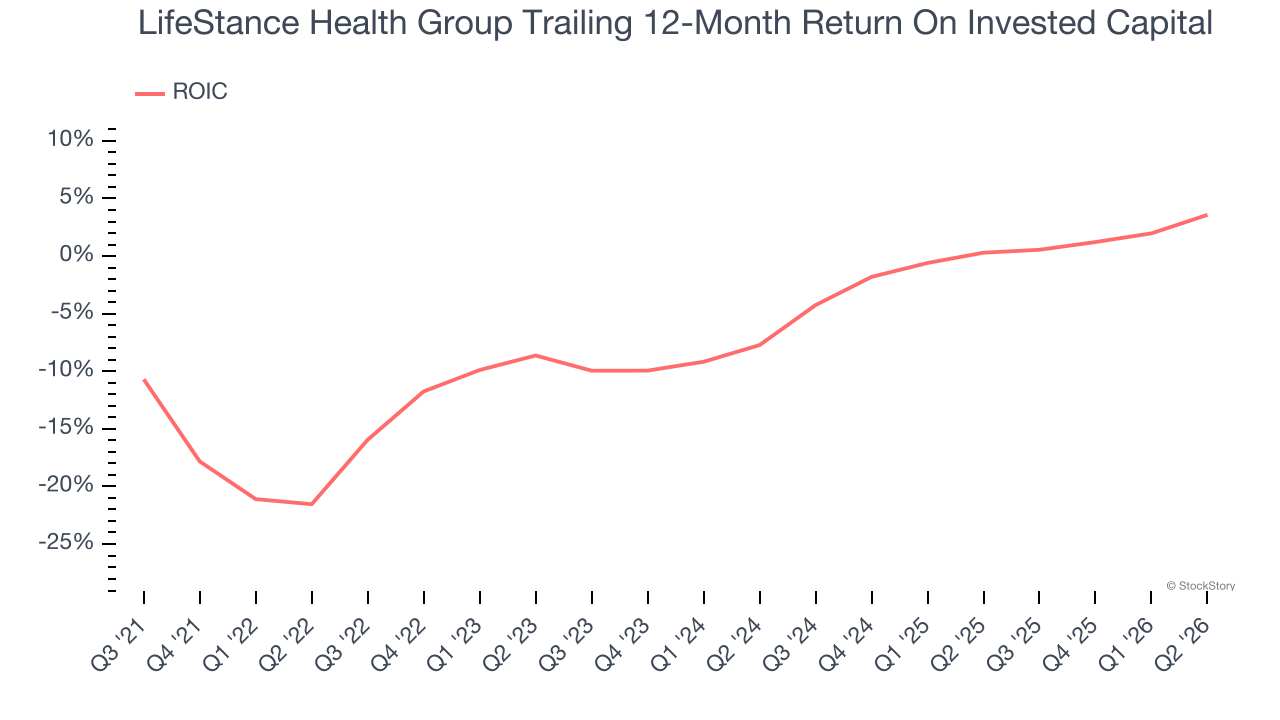
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? A company’s ROIC explains this by showing how much operating profit it makes compared to the money it has raised (debt and equity).
LifeStance Health Group’s five-year average ROIC was negative 6.8%, meaning management lost money while trying to expand the business. Its returns were among the worst in the healthcare sector.
Final Judgment
LifeStance Health Group isn’t a terrible business, but it doesn’t pass our quality test. After the recent rally, the stock trades at 30.5× forward P/E (or $12.58 per share). Beauty is in the eye of the beholder, but our analysis shows the upside isn’t great compared to the potential downside. We’re pretty confident there are superior stocks to buy right now. We’d recommend looking at the most dominant software business in the world.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.