What a time it’s been for Teradyne. In the past six months alone, the company’s stock price has increased by a massive 44.5%, reaching $399.20 per share. This was partly due to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is now the time to buy Teradyne, or should you be careful about including it in your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Is Teradyne Not Exciting?
We’re happy investors have made money, but we’re passing on Teradyne for now. Here are three reasons why TER doesn’t excite us, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
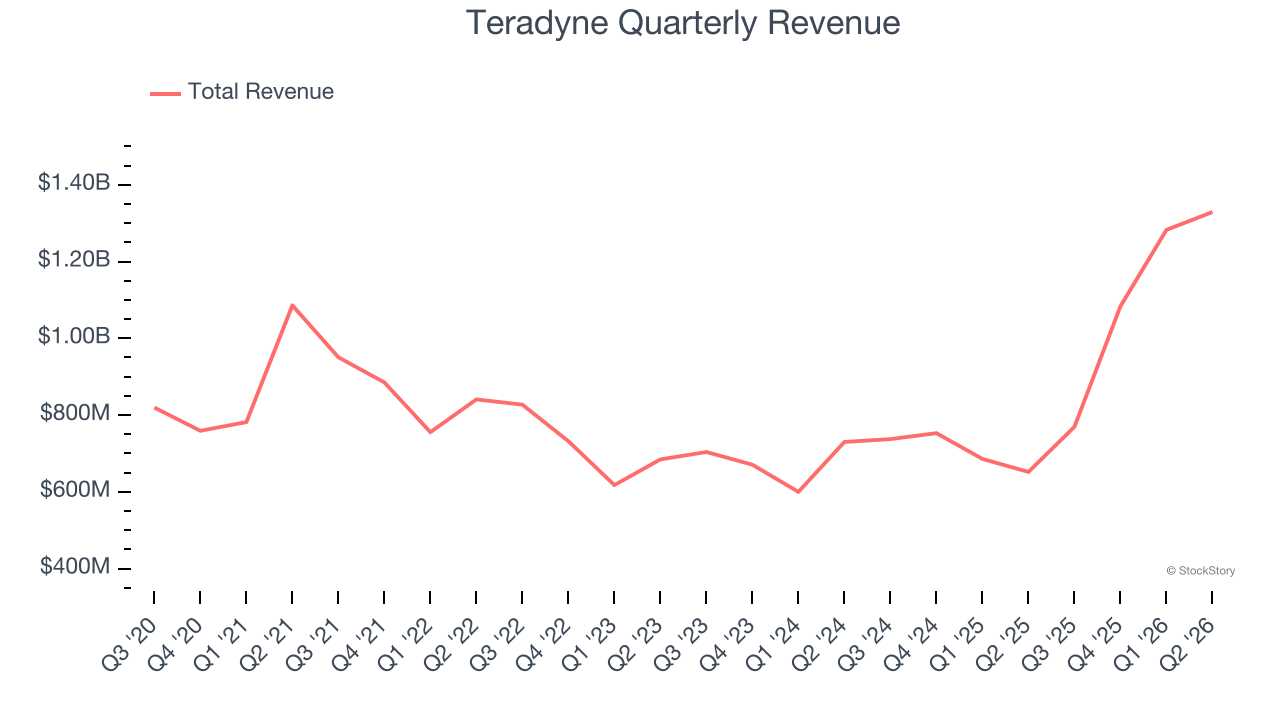
A company’s top-line performance can indicate its business quality. Rapid growth can signal it’s benefiting from an innovative new product or burgeoning market trend. Teradyne’s annualized revenue growth rate of 28.5% over the last two years was excellent for a semiconductor business. Semiconductors are a cyclical industry, and long-term investors should be prepared for periods of high growth followed by periods of revenue contractions.
2. Projected Revenue Growth Is Slim
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Teradyne’s revenue to rise by 24.4%, a deceleration versus its 5.3% annualized growth for the past five years. This projection doesn’t excite us and indicates its products and services will see some demand headwinds.
3. Free Cash Flow Margin Dropping
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
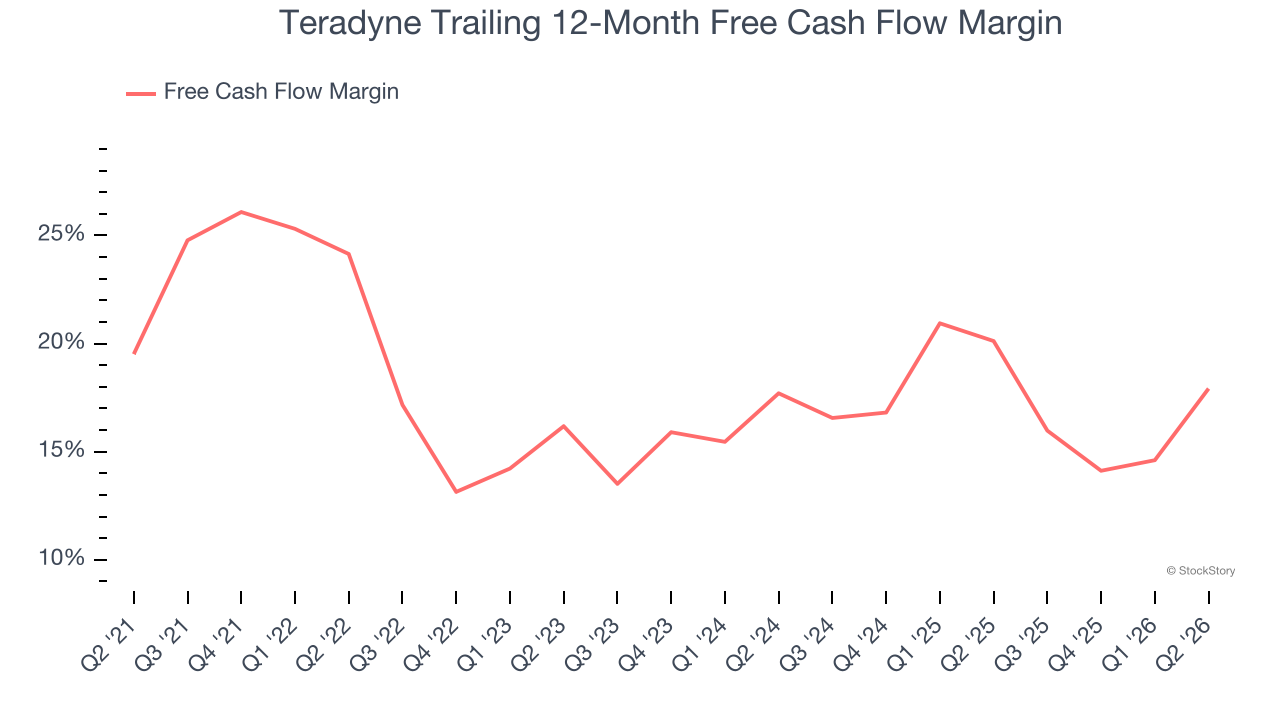
As you can see below, Teradyne’s margin dropped by 6.2 percentage points over the last five years. This along with its unexciting margin puts the company in a tough spot, and shareholders are likely hoping it can reverse course. If the trend continues, it could signal it’s becoming a more capital-intensive business. Teradyne’s free cash flow margin for the trailing 12 months was 17.9%.
Final Judgment
Teradyne isn’t a terrible business, but it isn’t one of our picks. After the recent surge, the stock trades at 39.8× forward P/E (or $399.20 per share). While this valuation is reasonable, we don’t really see a big opportunity at the moment. We’re pretty confident there are more exciting stocks to buy at the moment. We’d recommend looking at a dominant aerospace business that has perfected its M&A strategy.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.