Prudential has had an impressive run over the past six months as its shares have beaten the S&P 500 by 14.8%. The stock now trades at $115.75, marking a 21.1% gain. This run-up might have investors contemplating their next move.
Is there a buying opportunity in Prudential, or does it present a risk to your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why do we think Prudential will underperform?
We’re glad investors have benefited from the price increase, but we don’t have much confidence in Prudential. Here are three reasons we avoid PRU, plus one stock we’d rather own.
1. Declining net premiums earned reflect weakness
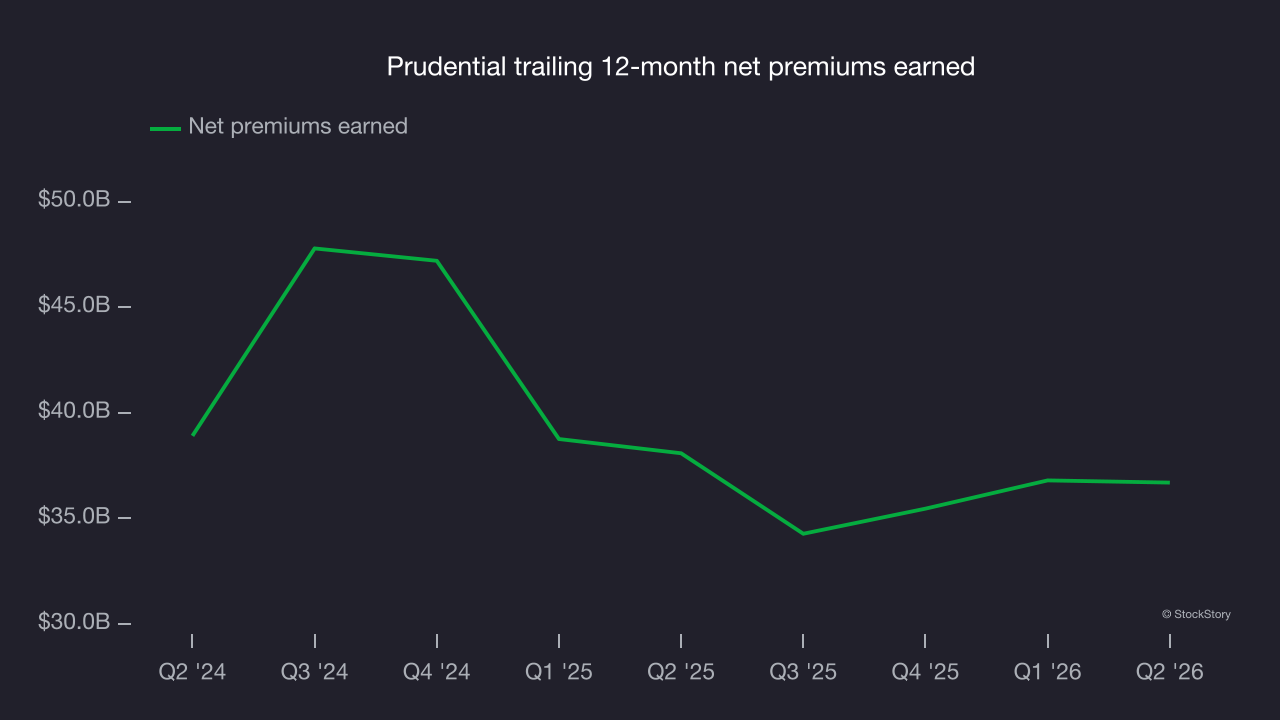
When insurers sell policies, they protect themselves from extremely large losses or an outsized accumulation of losses with reinsurance (insurance for insurance companies). Net premiums earned are therefore net of what’s ceded to reinsurers as a risk mitigation and transfer strategy.
Prudential’s net premiums earned has declined by 2.9% annually over the last two years, much worse than the broader insurance industry. This shows that policy underwriting underperformed its other business lines.
2. Substandard BVPS growth indicates limited asset expansion
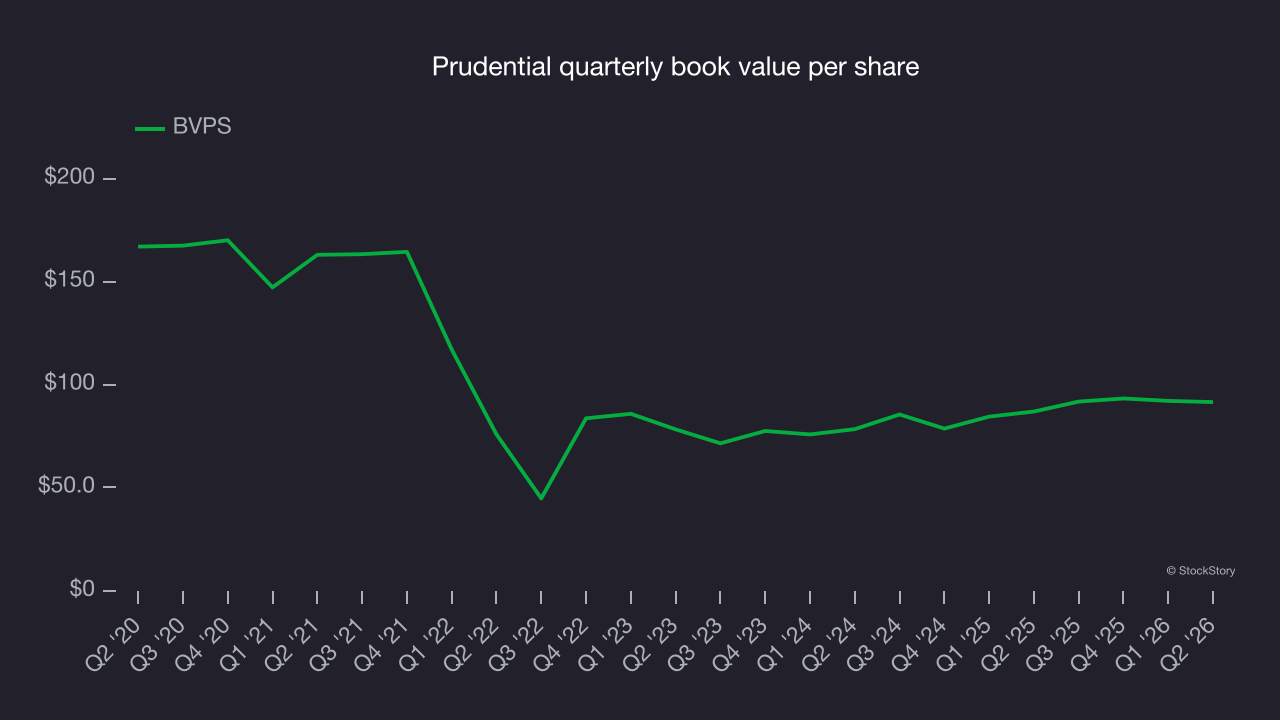
In the insurance industry, book value per share (BVPS) provides a clear picture of shareholder value, as it represents the total equity backing a company’s insurance operations and growth initiatives.
To the detriment of investors, Prudential’s BVPS grew at a tepid 8.1% annual clip over the last two years.
3. High debt levels increase risk
The debt-to-equity ratio is a widely used measure to assess a company’s balance sheet health. A higher ratio means that a business aggressively financed its growth with debt. This can result in higher earnings (if the borrowed funds are invested profitably) but also increases risk.
If debt levels are too high, there could be difficulties in meeting obligations, especially during economic downturns or periods of rising interest rates if the debt has variable-rate payments.
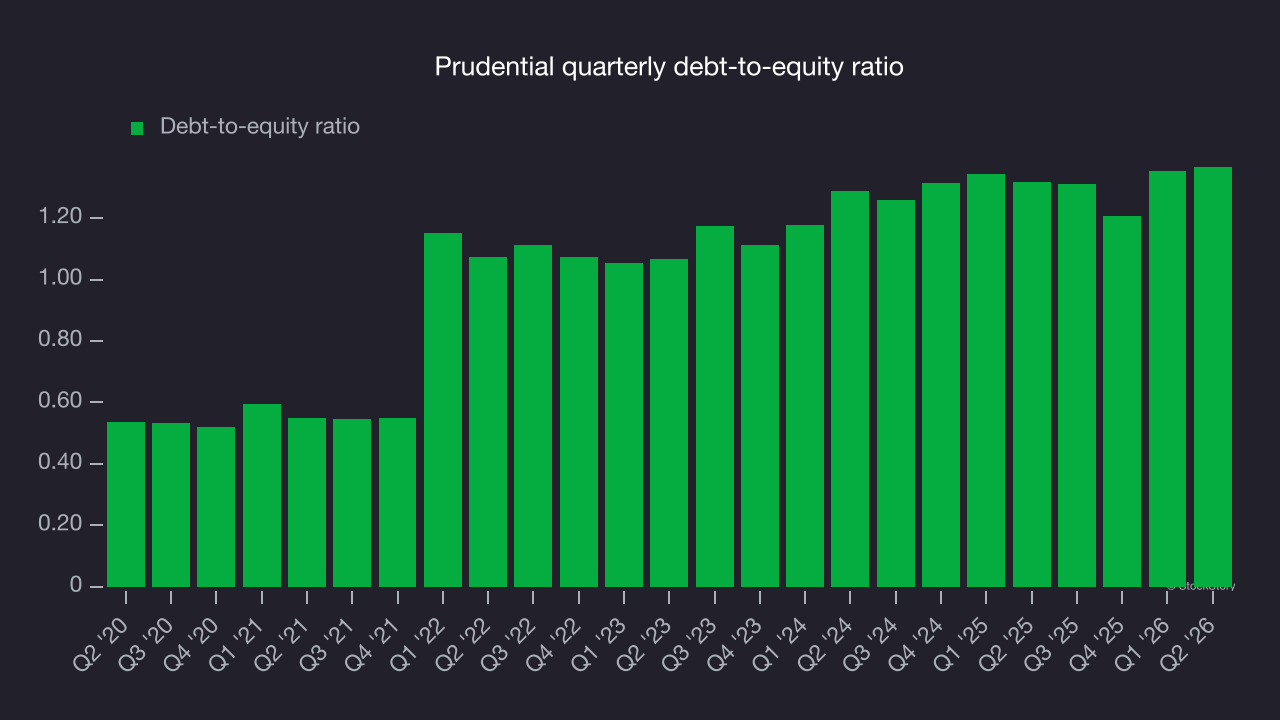
Prudential currently has $43.63 billion of debt and $31.94 billion of shareholders’ equity on its balance sheet, and over the past four quarters, has averaged a debt-to-equity ratio of 1.3×. We think this is dangerous - for an insurance business, anything above 1.0× raises red flags.
Final judgment
We cheer for all companies serving everyday consumers, but in the case of Prudential, we’ll be cheering from the sidelines. With its shares beating the market recently, the stock trades at 1.2× forward P/B (or $115.75 per share). This multiple tells us a lot of good news is priced in - we think there are better stocks to buy right now. We’d suggest looking at one of our top software and edge computing picks.
High-quality stocks for all market conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.