While the S&P 500 is up 12.8% since April 2026, Broadridge (currently trading at $165.46 per share) has lagged behind, posting a return of 5.1%. This may have investors wondering how to approach the situation.
Given the relatively weaker price action, is now a good time to buy BR, or is it a pass? Find out in our full research report, it’s free.
Why Are We Positive on Broadridge?
Processing over $10 trillion in equity and fixed income trades daily and managing proxy voting for over 800 million equity positions, Broadridge Financial Solutions (NYSE: BR) provides technology-driven solutions that power investing, governance, and communications for banks, broker-dealers, asset managers, and public companies.
1. Long-Term Revenue Growth Shows Strong Momentum
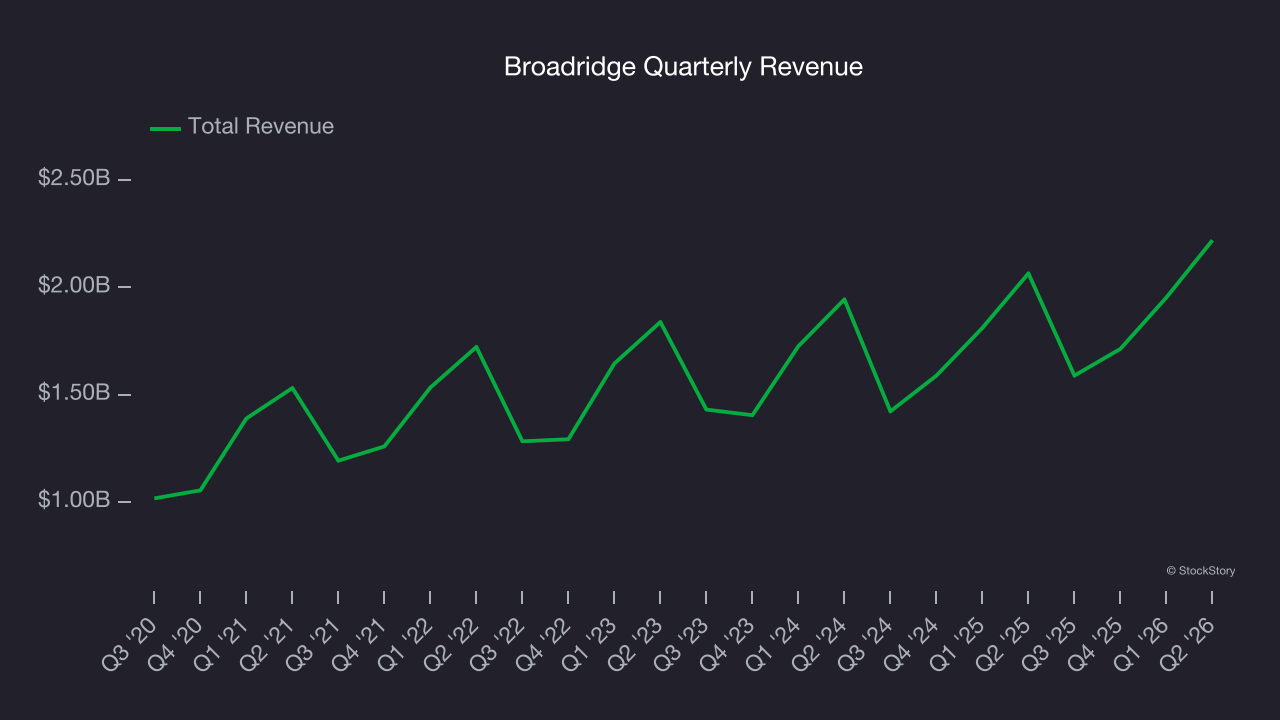
Examining a company’s long-term performance can provide clues about its quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Thankfully, Broadridge’s 8.4% annualized revenue growth over the last five years was solid. Its growth beat the average business services company and shows its offerings resonate with customers.
2. Increasing Free Cash Flow Margin Juices Financials
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
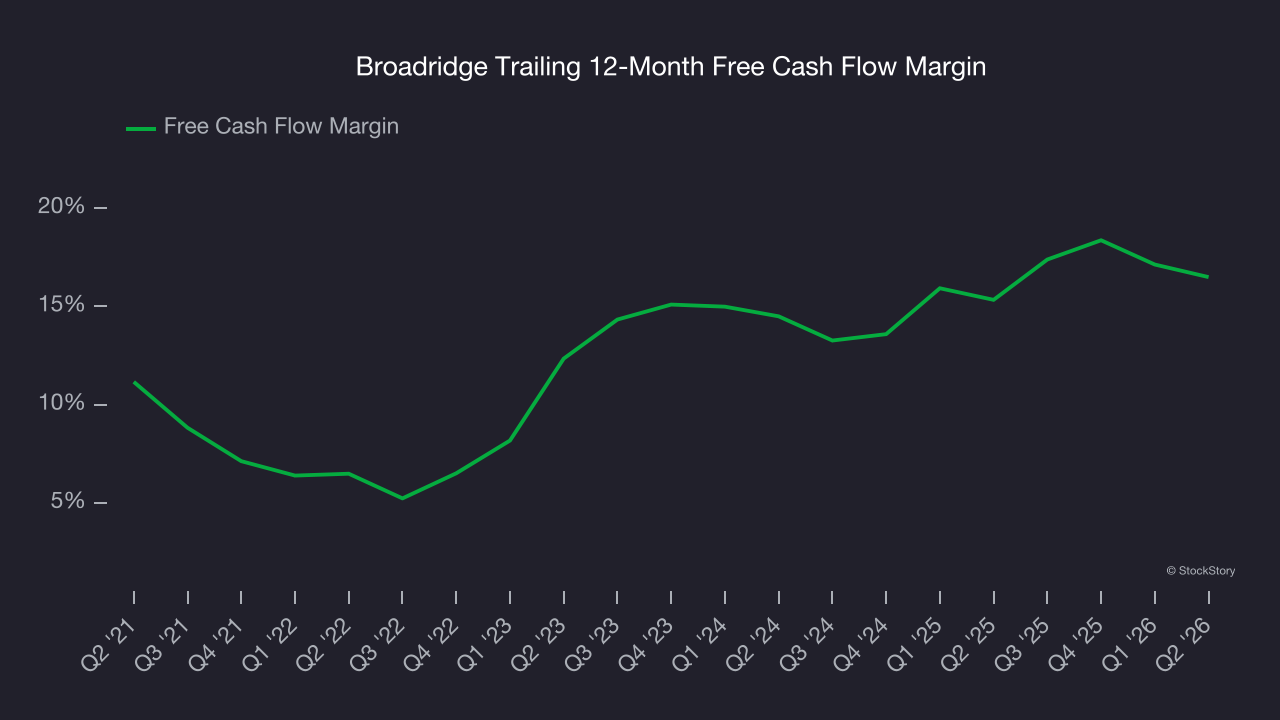
As you can see below, Broadridge’s margin expanded by 10 percentage points over the last five years. This is encouraging, and we can see it became a less capital-intensive business because its free cash flow profitability rose more than its operating profitability. Broadridge’s free cash flow margin for the trailing 12 months was 16.5%.
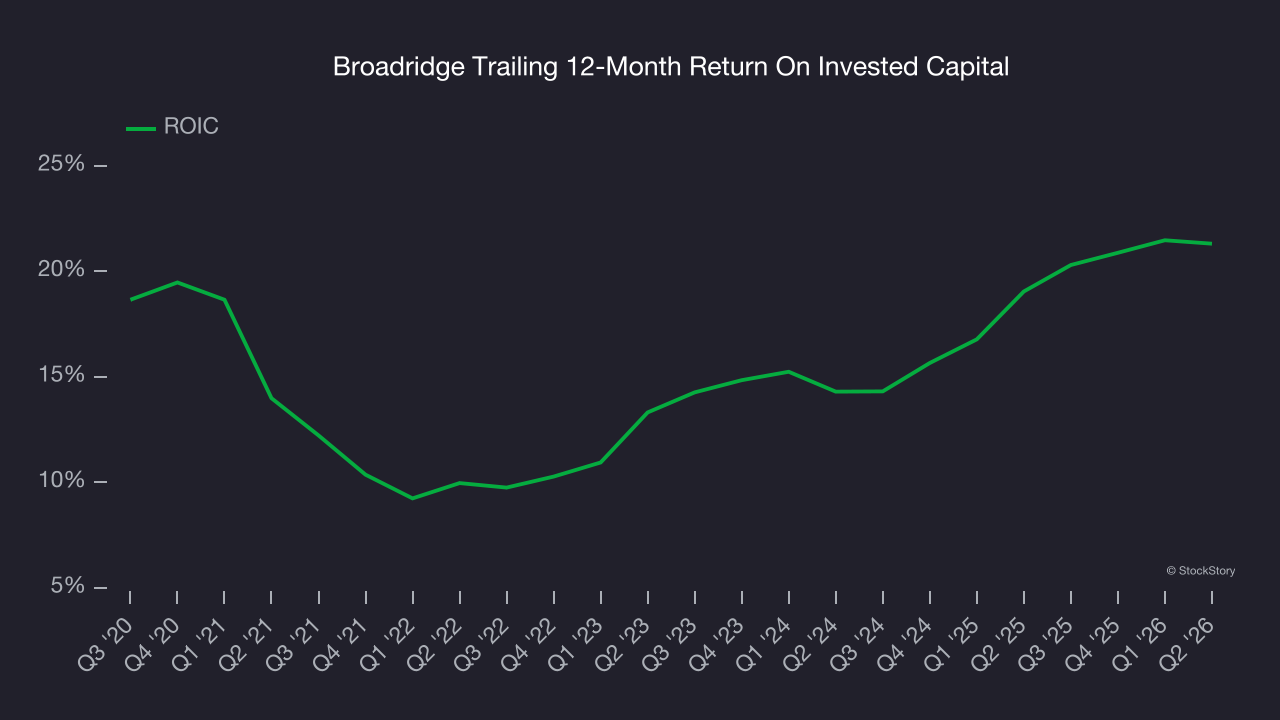
3. New Investments Bear Fruit as ROIC Jumps
ROIC, or return on invested capital, is a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
Fortunately, Broadridge’s ROIC has increased over the last few years. This is a great sign when paired with its already strong returns. It could suggest its competitive advantage or profitable growth opportunities are expanding.
Final Judgment
These are just a few reasons why we’re bullish on Broadridge. With its shares lagging the market recently, the stock trades at 15.6× forward P/E (or $165.46 per share). Is now a good time to buy? See for yourself in our comprehensive research report, it’s free.
Stocks We Like Even More Than Broadridge
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.