What a time it’s been for Integer Holdings. In the past six months alone, the company’s stock price has increased by a massive 44.4%, setting a new 52-week high of $126.66 per share. This was partly thanks to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is there a buying opportunity in Integer Holdings, or does it present a risk to your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Is Integer Holdings Not Exciting?
We’re glad investors have benefited from the price increase, but we’re cautious about Integer Holdings. Here are three reasons why there are better opportunities than ITGR, plus one stock we’d rather own.
1. Lackluster Revenue Growth
We at StockStory place the most emphasis on long-term growth, but within healthcare, a stretched historical view may miss recent innovations or disruptive industry trends. Integer Holdings’s recent performance shows its demand has slowed as its annualized revenue growth of 6.1% over the last two years was below its five-year trend. We’re wary when companies in the sector see decelerations in revenue growth, as it could signal changing consumer tastes aided by low switching costs. 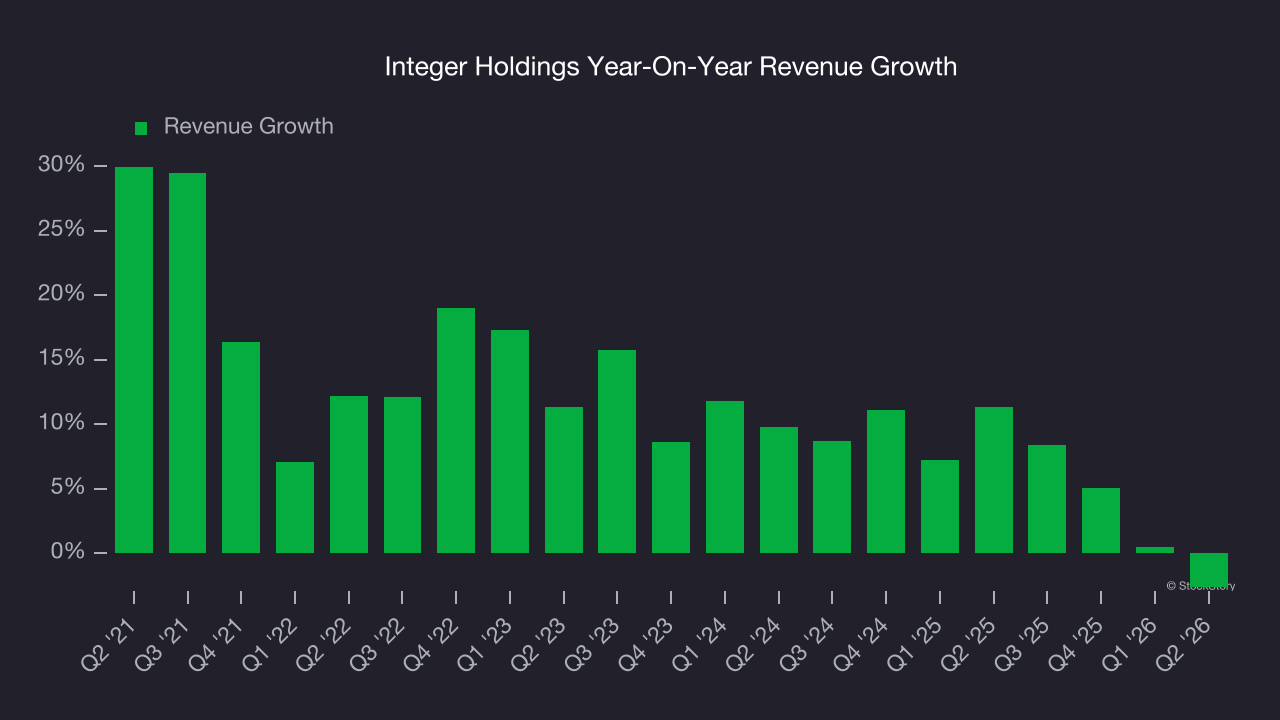
2. Fewer Distribution Channels Limit Its Ceiling
Larger companies benefit from economies of scale, where fixed costs like infrastructure, technology, and administration are spread over a higher volume of goods or services, reducing the cost per unit. Scale can also lead to bargaining power with suppliers, greater brand recognition, and more investment firepower. A virtuous cycle can ensue if a scaled company plays its cards right.
With just $1.84 billion in revenue over the past 12 months, Integer Holdings is a small company in an industry where scale matters. This makes it difficult to build trust with customers because healthcare is heavily regulated, complex, and resource-intensive.
3. Projected Revenue Growth Is Slim
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Integer Holdings’s revenue to rise by 1.5%, a deceleration versus its 10.7% annualized growth for the past five years. This projection is underwhelming and implies its products and services will face some demand challenges.
Final Judgment
Integer Holdings isn’t a terrible business, but it doesn’t pass our quality test. Following the recent rally, the stock trades at 18.9× forward P/E (or $126.66 per share). This valuation is reasonable, but the company’s shakier fundamentals present too much downside risk. We’re fairly confident there are better stocks to buy right now. We’d recommend looking at the Amazon and PayPal of Latin America.
Stocks We Would Buy Instead of Integer Holdings
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.