What a fantastic six months it’s been for Micron. Shares of the company have skyrocketed 141%, hitting $1,029. This was partly thanks to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is it too late to buy MU? Find out in our full research report, it’s free.
Why Is Micron a Good Business?
Founded in the basement of a Boise, Idaho dental office in 1978, Micron (NASDAQ: MU) is a leading provider of memory chips used in thousands of devices across mobile, data centers, industrial, consumer, and automotive markets.
1. Skyrocketing Revenue Shows Strong Momentum
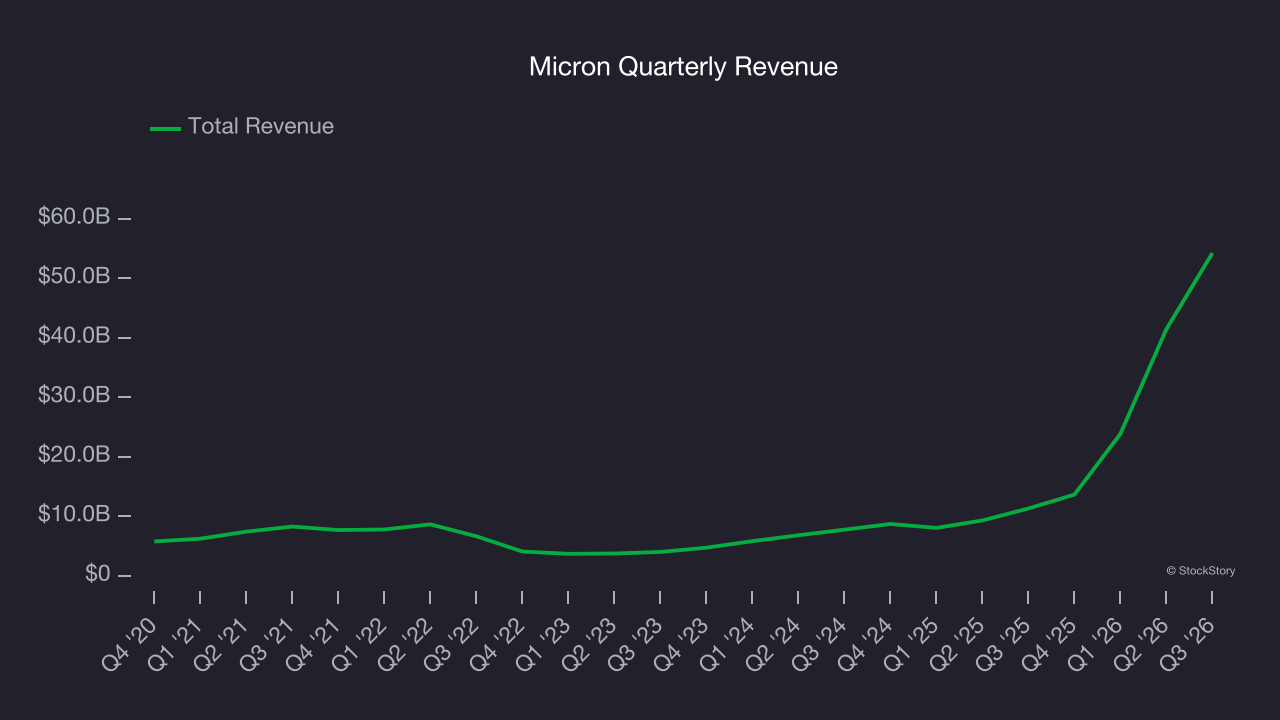
A company’s long-term sales performance is one signal of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Thankfully, Micron’s 36.9% annualized revenue growth over the last five years was incredible. Its growth surpassed the average semiconductor company and shows its offerings resonate with customers. Semiconductors are a cyclical industry, and long-term investors should be prepared for periods of high growth followed by periods of revenue contractions (which can sometimes offer opportune times to buy).
2. Outstanding Long-Term EPS Growth
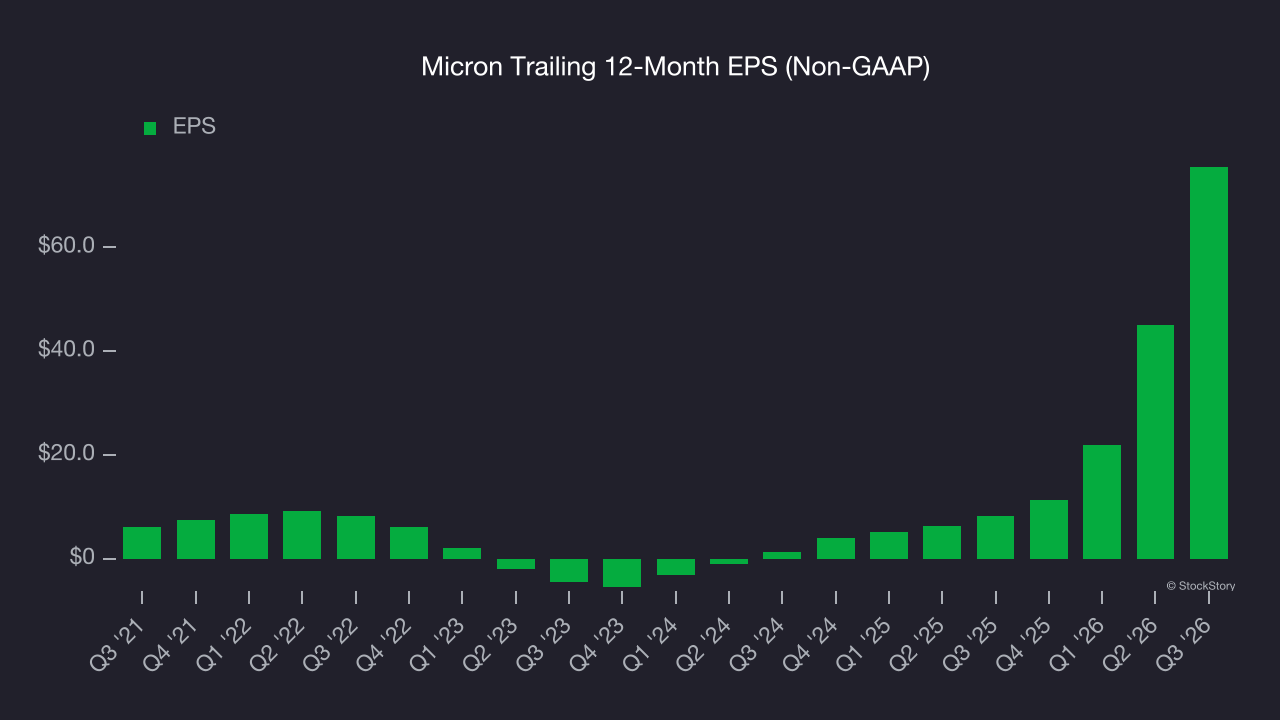
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Micron’s EPS grew at 65.6% compounded annual growth rate over the last five years, higher than its 36.9% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
3. Excellent Free Cash Flow Margin Boosts Reinvestment Potential
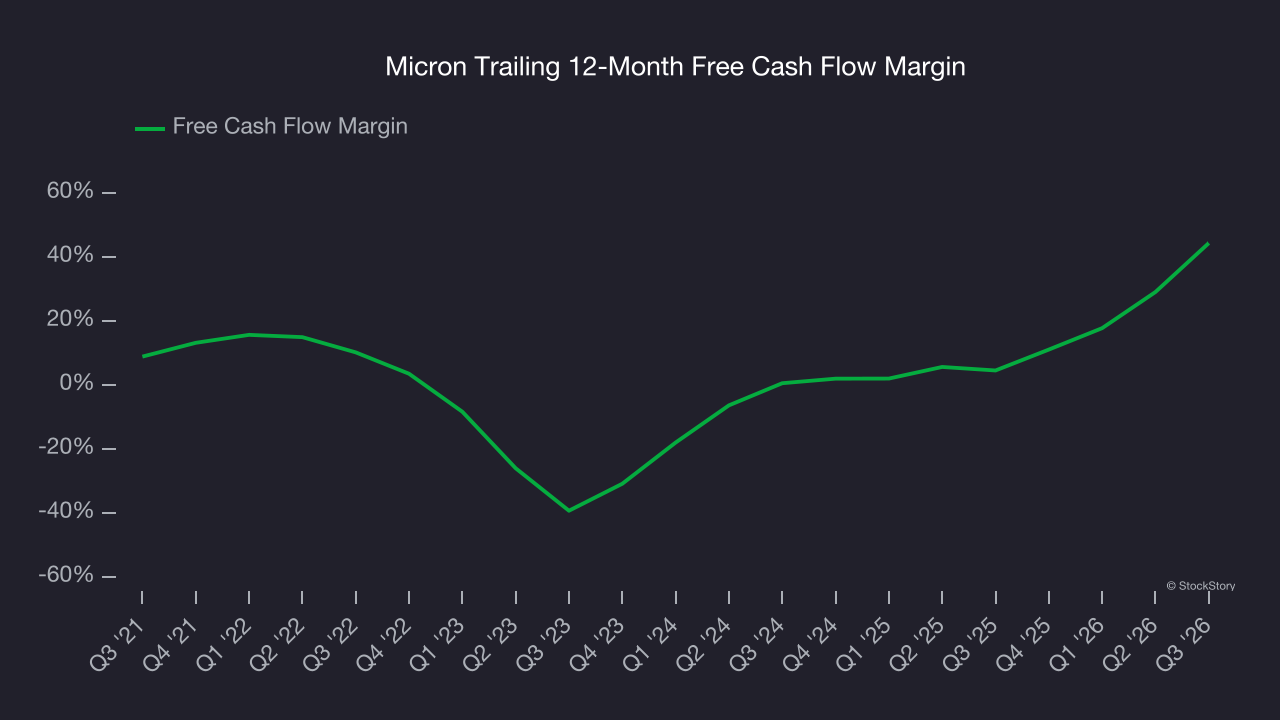
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
Micron has shown terrific cash profitability, and if sustainable, puts it in an advantageous position to invest in new products, return capital to investors, and consolidate the market during industry downturns. The company’s free cash flow margin was among the best in the semiconductor sector, averaging an eye-popping 35.5% over the last two years.
Final Judgment
These are just a few reasons why we think Micron is one of the best semiconductor companies out there, and after the recent rally, the stock trades at 5.9× forward P/E (or $1,029 per share). Is now the right time to buy? See for yourself in our in-depth research report, it’s free.
Stocks We Like Even More Than Micron
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.