Over the past six months, Texas Pacific Land’s shares (currently trading at $362) have posted a disappointing 13.1% loss, well below the S&P 500’s 12.8% gain. This might have investors contemplating their next move.
Following the pullback, is this a buying opportunity for TPL? Find out in our full research report, it’s free.
Why Is TPL a Good Business?
One of America's largest private landowners with roughly 868,000 acres in the Permian Basin, Texas Pacific Land (NYSE: TPL) owns land in West Texas and earns revenue from oil and gas royalties, water services, and land leases.
1. Skyrocketing Revenue Shows Strong Momentum
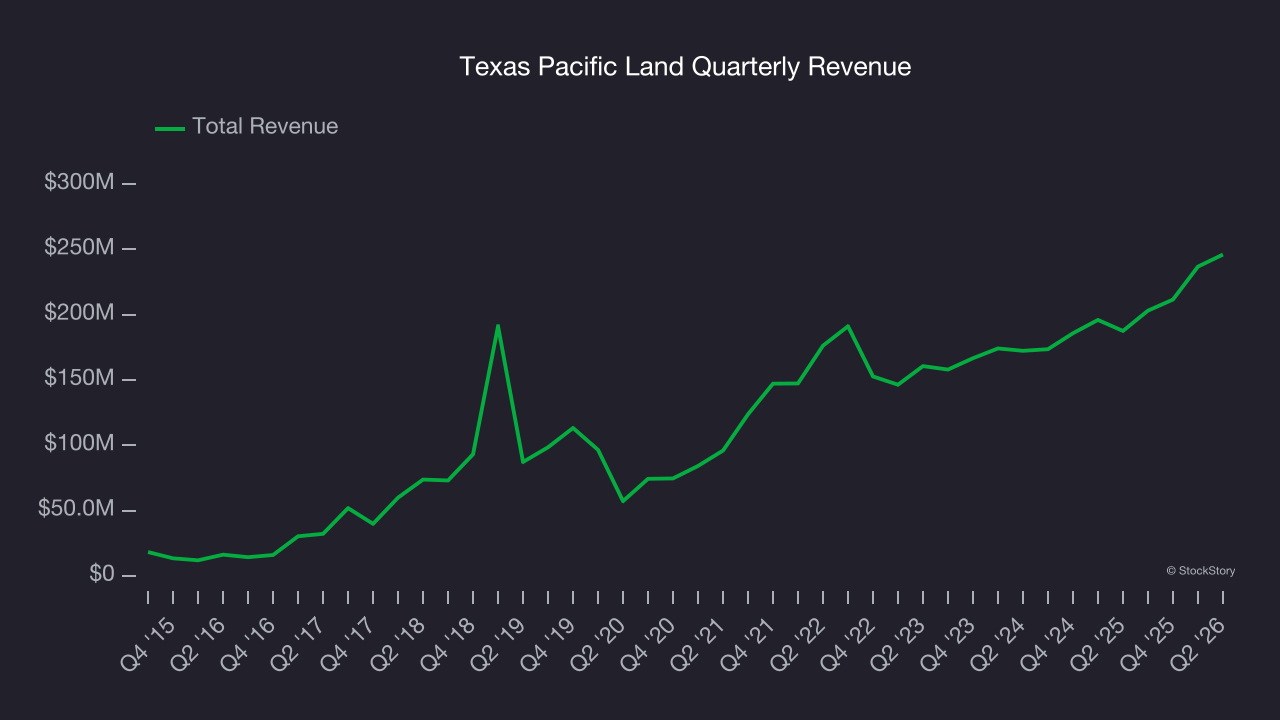
A company’s long-term performance can give signals about its business quality. Even a bad business, especially in a cyclical industry, can shine for a year or so, but a top-tier one should exhibit resilience through cycles. Luckily, Texas Pacific Land’s sales grew at an exceptional 22.2% compounded annual growth rate over the last five years. Its growth beat the average energy upstream and integrated energy company and shows its offerings resonate with customers.
2. Elite Gross Margin Powers Best-In-Class Business Model
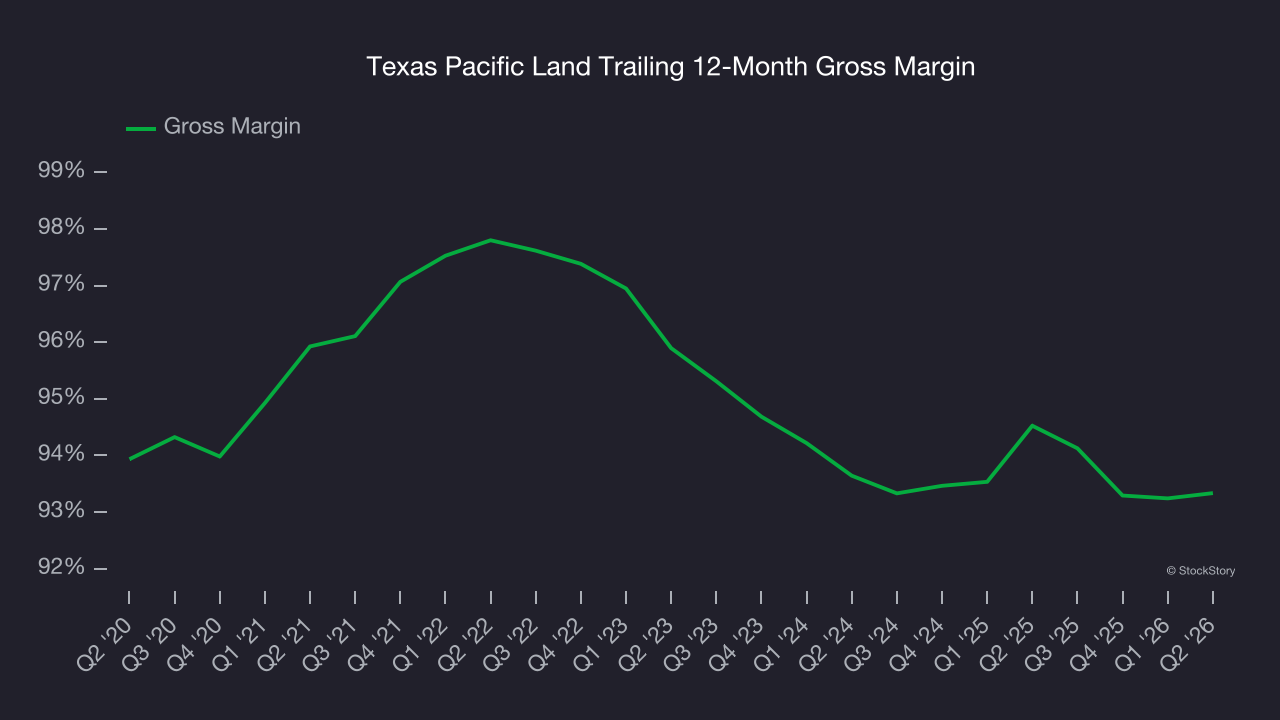
In a single quarter or year, gross margins in the sector can swing wildly due to commodity prices, hedging, or changes in labor costs. Over a multi-year period across different points in the cycle, gross margin differences can signal whether a company is a structurally-advantaged producer (“rock” quality, takeaway, operating costs) or not.
Texas Pacific Land, which averaged 94.9% gross margin over the last five years, exhibits enviable unit economics in the sector. It means the company will remain profitable at lower commodity prices than peers with inferior gross margins and serves as an advantaged starting point for ultimate operating profits and free cash flow generation.
3. Excellent Free Cash Flow Margin Boosts Reinvestment Potential
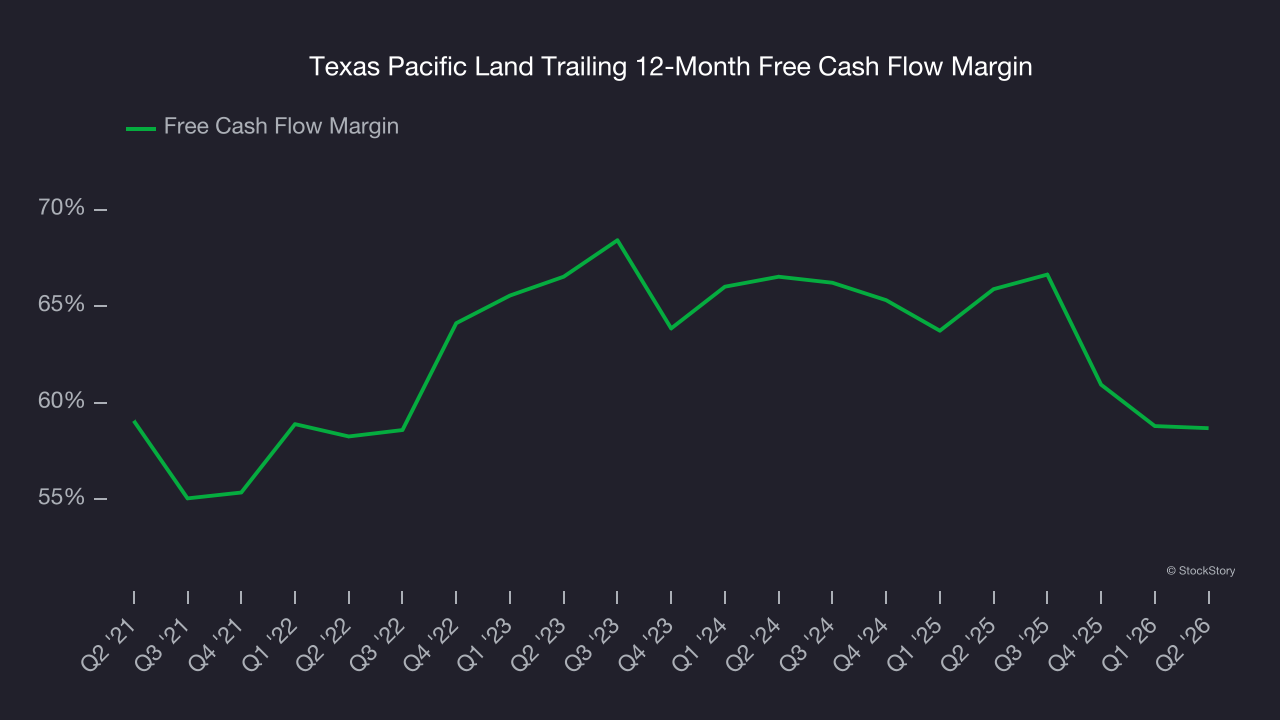
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
Texas Pacific Land has shown terrific cash profitability, driven by its lucrative business model that enables it to reinvest, return capital to investors, and stay ahead of the competition. The company’s free cash flow margin was among the best in the energy upstream and integrated energy sector, averaging an eye-popping 63% over the last five years.
Final Judgment
These are just a few reasons why we think Texas Pacific Land is an elite energy upstream and integrated energy company. After the recent drawdown, the stock trades at 24.9× forward EV-to-EBITDA (or $362 per share). Is now the right time to buy? See for yourself in our comprehensive research report, it’s free.
Stocks We Like Even More Than Texas Pacific Land
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.