Quarterly earnings results are a good time to check in on a company’s progress, especially compared to its peers in the same sector. Today we are looking at Diamondback Energy (NASDAQ: FANG) and the best and worst performers in the u.s. shale e&p industry.
US shale oil producers extract crude from tight rock formations using horizontal drilling and hydraulic fracturing (fracking) techniques, primarily in basins like the Permian, Bakken, and Eagle Ford. Tailwinds include short-cycle investment flexibility allowing rapid production adjustments, technological improvements enhancing well productivity, and proximity to refining and export infrastructure. Capital discipline has improved financial returns. Headwinds include commodity price sensitivity affecting drilling economics, accelerating well decline rates requiring continuous capital investment, and increasing regulatory and ESG scrutiny. Water usage, induced seismicity concerns, and evolving environmental regulations present ongoing operational challenges.
The 11 u.s. shale e&p stocks we track reported an exceptional Q2. As a group, revenues beat analysts’ consensus estimates by 10.4%.
Luckily, u.s. shale e&p stocks have performed well with share prices up 20.6% on average since the latest earnings results.
Diamondback Energy (NASDAQ: FANG)
Sporting one of Wall Street's most memorable ticker symbols, Diamondback Energy (NASDAQ: FANG) drills for and produces oil and natural gas from underground rock formations in the Permian Basin of West Texas and New Mexico.
Diamondback Energy reported revenues of $5.56 billion, up 51.2% year on year. This print exceeded analysts’ expectations by 13.5%. Overall, it was an exceptional quarter for the company with a solid beat of analysts’ EBITDA estimates and a beat of analysts’ EPS estimates.
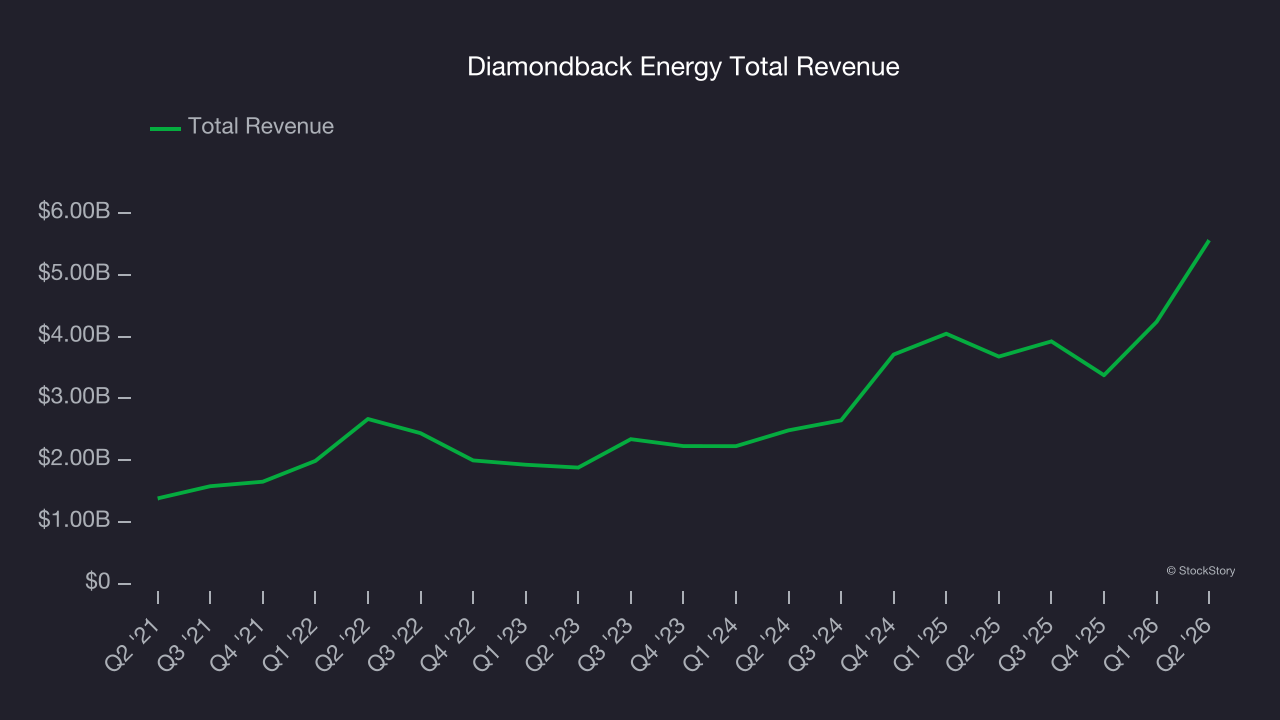
Interestingly, the stock is up 2.1% since reporting and currently trades at $202.97.
Best Q2: Matador Resources (NYSE: MTDR)
Operating primarily in the Delaware Basin where multiple oil-bearing layers lie stacked thousands of feet deep, Matador Resources (NYSE: MTDR) explores for, drills, and produces oil and natural gas from underground rock formations in New Mexico and Texas.
Matador Resources reported revenues of $1.19 billion, up 32.5% year on year, outperforming analysts’ expectations by 13.7%. The business had an incredible quarter with a beat of analysts’ EPS estimates and an impressive beat of analysts’ EBITDA estimates.
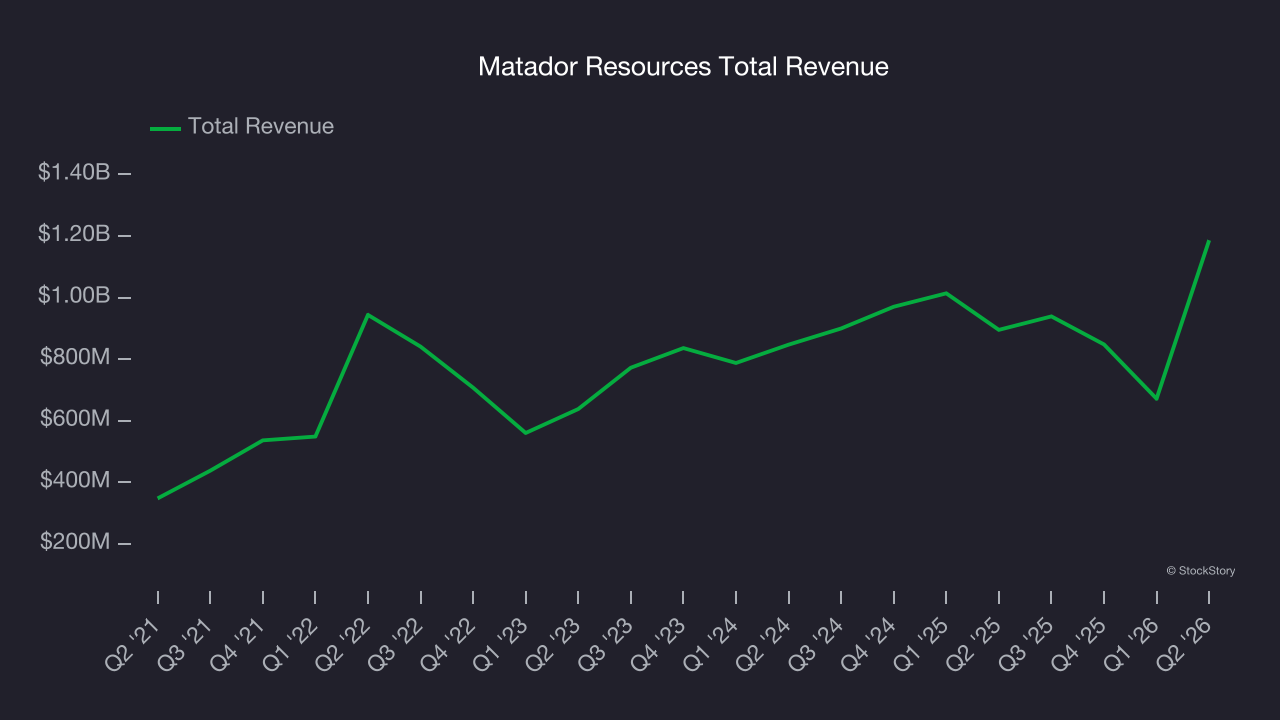
The market seems happy with the results as the stock is up 23.1% since reporting. It currently trades at $57.88.
Is now the time to buy Matador Resources? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: Texas Pacific Land (NYSE: TPL)
One of America's largest private landowners with roughly 868,000 acres in the Permian Basin, Texas Pacific Land (NYSE: TPL) owns land in West Texas and earns revenue from oil and gas royalties, water services, and land leases.
Texas Pacific Land reported revenues of $246.1 million, up 31.2% year on year, falling short of analysts’ expectations by 1.4%. It was a mixed quarter as it posted a decent beat of analysts’ EBITDA estimates.
Texas Pacific Land delivered the weakest performance against analyst estimates in the group. As expected, the stock is down 9.8% since the results and currently trades at $344.63.
Read our full analysis of Texas Pacific Land’s results here.
Chord Energy (NASDAQ: CHRD)
Holding the largest acreage position in the Williston Basin, Chord Energy (NASDAQ: CHRD) drills for and produces crude oil, natural gas liquids, and natural gas in North Dakota's Williston Basin.
Chord Energy reported revenues of $2.17 billion, up 84% year on year. This result topped analysts’ expectations by 31.9%. Overall, it was a very strong quarter for the company.
Chord Energy scored the biggest analyst estimate beat among its peers. The stock is up 16.1% since reporting and currently trades at $150.94.
Read our full, actionable report on Chord Energy here, it’s free.
Northern Oil and Gas (NYSE: NOG)
Taking the path less traveled in the oil industry by choosing not to operate its own wells, Northern Oil and Gas (NYSE: NOG) acquires minority stakes in oil and gas wells operated by other companies across major U.S. shale basins.
Northern Oil and Gas reported revenues of $588.7 million, down 7.9% year on year. This print beat analysts’ expectations by 1.7%. Overall, it was a very strong quarter as it also logged a solid beat of analysts’ EBITDA estimates and EPS in line with analysts’ estimates.
Northern Oil and Gas had the slowest revenue growth in the group. The stock is up 34.8% since reporting and currently trades at $27.33.
Read our full, actionable report on Northern Oil and Gas here, it’s free.
Market update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Hidden Gem Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.