The end of the earnings season is always a good time to take a step back and see who shined (and who didn’t). Let’s take a look at how consumer discretionary - travel and vacation providers stocks fared in Q2, starting with Carnival (NYSE: CCL).
The Consumer Discretionary sector, by definition, is made up of companies selling non-essential goods and services. When economic conditions deteriorate or tastes shift, consumers can easily cut back or eliminate these purchases. For long-term investors with five-year holding periods, this creates a structural challenge: the sector is inherently hit-driven, with low switching costs and fickle customers. As a result, only a handful of companies can reliably grow demand and compound earnings over long periods, which is why our bar is high and High Quality ratings are rare. Travel and vacation providers operate tour packages, cruise lines, online travel agencies, and vacation rental platforms, connecting consumers with leisure and business travel experiences. Tailwinds include robust post-pandemic travel demand, a consumer preference shift toward experiences over goods, and technology-enabled personalization improving conversion and loyalty. However, headwinds are significant: the industry is acutely sensitive to macroeconomic cycles, geopolitical instability, and fuel price volatility. Low switching costs mean fierce price competition, while capacity additions in segments like cruises can lead to oversupply. Regulatory burdens, weather disruptions, and public health risks further create episodic but potentially severe demand shocks.
The 19 consumer discretionary - travel and vacation providers stocks we track reported a satisfactory Q2. As a group, revenues beat analysts’ consensus estimates by 1.3% while next quarter’s revenue guidance was 0.6% above.
Amidst this news, share prices of the companies have had a rough stretch. On average, they are down 9.2% since the latest earnings results.
Carnival (NYSE: CCL)
Boasting outrageous amenities like a planetarium on board its ships, Carnival (NYSE: CCL) is one of the world's largest leisure travel companies and a prominent player in the cruise industry.
Carnival reported revenues of $6.66 billion, up 5.3% year on year. This print was in line with analysts’ expectations, but overall, it was a mixed quarter for the company with a beat of analysts’ EPS estimates but EBITDA guidance for next quarter missing analysts’ expectations.
"We achieved another quarter of record results, marking our twelfth consecutive quarter of record net yields and delivering over 20 percent more to the bottom line, overcoming extreme geopolitical headwinds and nearly 30 percent higher fuel costs. Continued commercial execution and a step up in our cost efficiency efforts enabled us to exceed our March guidance by $100 million. These results reflect the strong demand for our portfolio of world-class cruise lines and the continued progress we are making across the business," said Carnival Corporation's Chief Executive Officer Josh Weinstein.
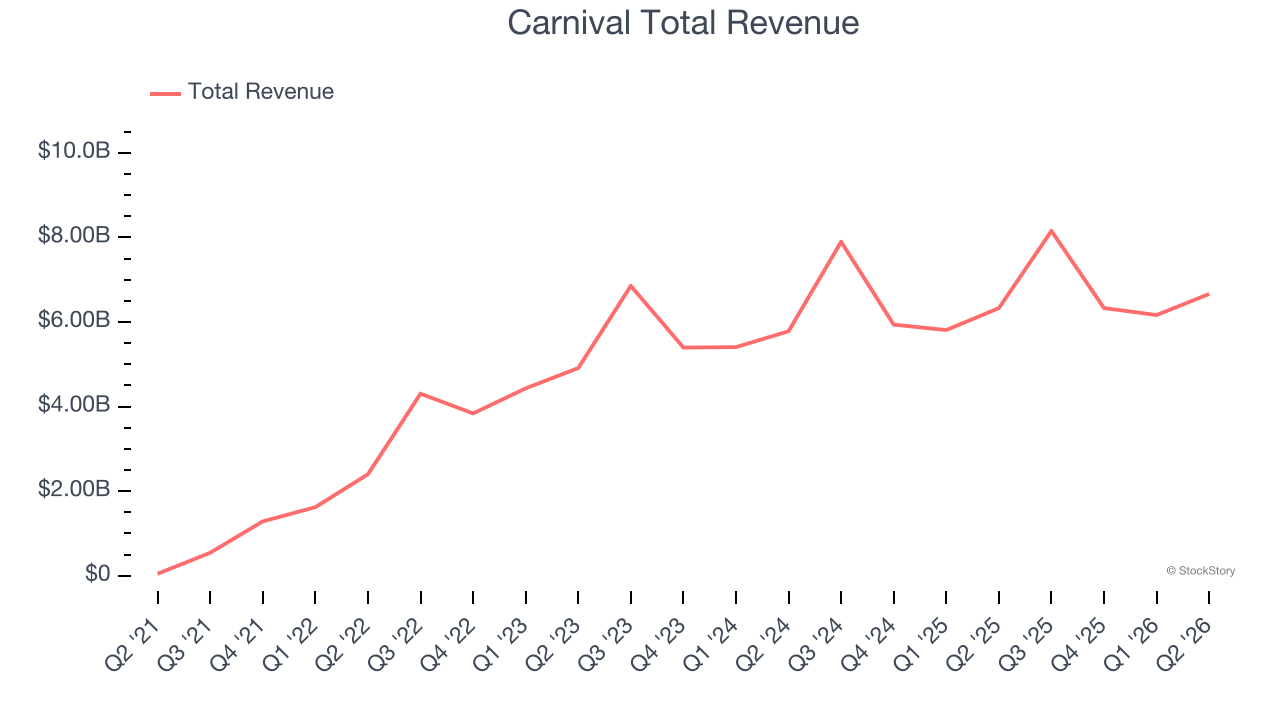
The market seems disappointed with the results as the stock is down 26.7% since reporting and currently trades at $22.14.
Is now the time to buy Carnival? Access our full analysis of the earnings results here, it’s free.
Best Q2: Target Hospitality (NASDAQ: TH)
Building mini-communities at places such as oil drilling sites, Target Hospitality (NASDAQ: TH) is a provider of specialty workforce lodging accommodations and services.
Target Hospitality reported revenues of $85.46 million, up 38.7% year on year, outperforming analysts’ expectations by 7.8%. The business had an incredible quarter with a beat of analysts’ EPS estimates and an impressive beat of analysts’ EBITDA estimates.
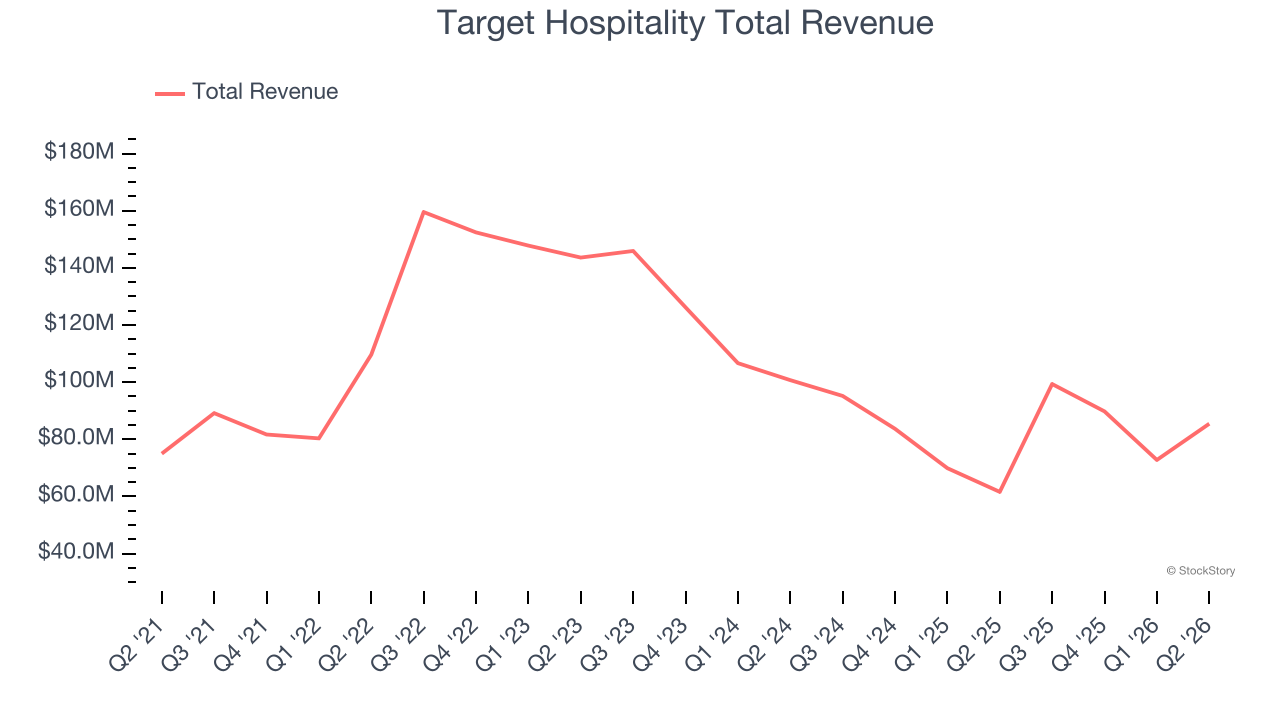
Target Hospitality achieved the biggest analyst estimate beat, fastest revenue growth, and highest full-year guidance raise among its peers. The market seems happy with the results as the stock is up 17% since reporting. It currently trades at $19.32.
Is now the time to buy Target Hospitality? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: Hilton Grand Vacations (NYSE: HGV)
Spun off from Hilton Worldwide in 2017, Hilton Grand Vacations (NYSE: HGV) is a global timeshare company that provides travel experiences for its customers through its timeshare resorts and club membership programs.
Hilton Grand Vacations reported revenues of $1.36 billion, up 7.3% year on year, falling short of analysts’ expectations by 2.7%. It was a softer quarter as it posted a significant miss of analysts’ EPS estimates and a miss of analysts’ EBITDA estimates.
As expected, the stock is down 30.1% since the results and currently trades at $35.95.
Read our full analysis of Hilton Grand Vacations’s results here.
Hyatt Hotels (NYSE: H)
Founded in 1957, Hyatt Hotels (NYSE: H) is a global hospitality company with a portfolio of 20 premier brands and over 950 properties across 65 countries.
Hyatt Hotels reported revenues of $1.83 billion, up 1.2% year on year. This number topped analysts’ expectations by 0.5%. It was a satisfactory quarter as it also logged a beat of analysts’ EPS estimates.
The stock is down 13.3% since reporting and currently trades at $161.26.
Read our full, actionable report on Hyatt Hotels here, it’s free.
Delta (NYSE: DAL)
One of the ‘Big Four’ airlines in the US, Delta Air Lines (NYSE: DAL) is a major global air carrier that serves both business and leisure travelers through its domestic and international flights.
Delta reported revenues of $19.76 billion, up 18.7% year on year. This result surpassed analysts’ expectations by 3.9%. Overall, it was a stunning quarter as it also recorded a beat of analysts’ EPS estimates and full-year EPS guidance exceeding analysts’ expectations.
The stock is down 5.6% since reporting and currently trades at $83.98.
Read our full, actionable report on Delta here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Top 5 Quality Compounder Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.