Even though Hilton (currently trading at $323.84 per share) has gained 9.5% over the last six months, it has lagged the S&P 500’s 21.1% return during that period. This may have investors wondering how to approach the situation.
Is there a buying opportunity in Hilton, or does it present a risk to your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Do We Think Hilton Will Underperform?
We’re cautious about Hilton. Here are three reasons we avoid HLT, plus one stock we’d rather own.
1. RevPAR Hits a Plateau
Investors interested in Consumer Discretionary - Travel and Vacation Providers companies should track RevPAR (revenue per available room) in addition to reported revenue. This metric accounts for daily rates and occupancy levels, painting a holistic picture of Hilton’s demand characteristics.
Over the last two years, Hilton failed to grow its RevPAR, which came in at $125.02 in the latest quarter. This performance was underwhelming and implies there may be increasing competition or market saturation. It also suggests Hilton might have to invest in new amenities such as restaurants and bars to attract customers - this isn’t ideal because expansions can complicate operations and be quite expensive (i.e., renovations and increased overhead). 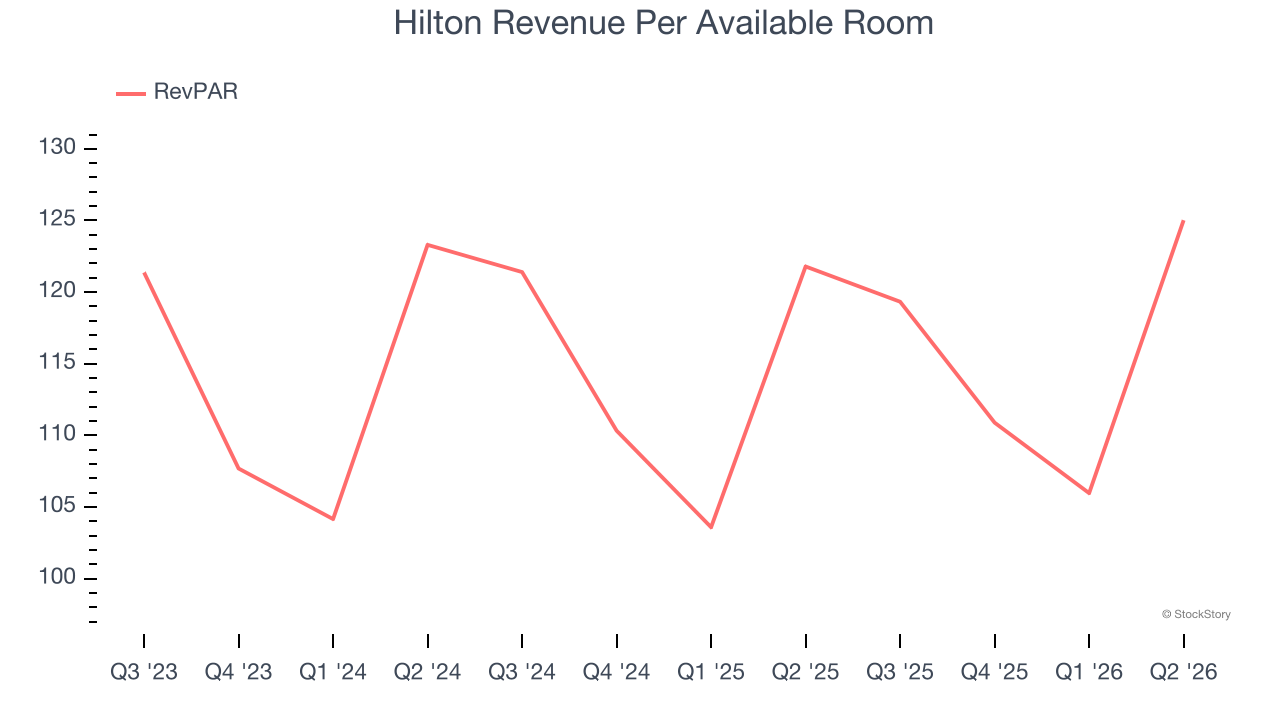
2. Weak Operating Margin Could Cause Trouble
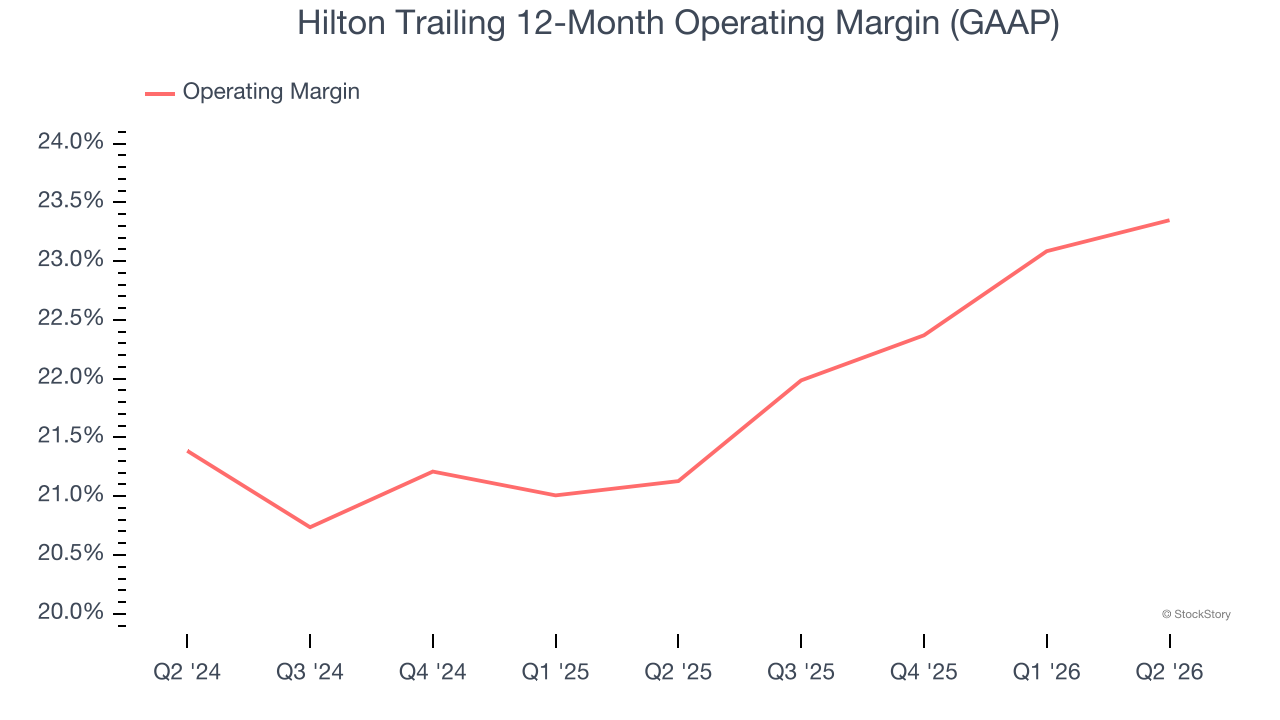
Operating margin is a key measure of profitability. Think of it as net income - the bottom line - excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
Hilton’s operating margin has been trending up over the last 12 months and averaged 22.3% over the last two years. The company’s higher efficiency is a breath of fresh air, but its suboptimal cost structure means it still sports lousy profitability for a consumer discretionary business.
3. Free Cash Flow Projections Disappoint
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Over the next year, analysts’ consensus estimates show they’re expecting Hilton’s free cash flow margin of 16.3% for the last 12 months to remain the same.
Final Judgment
We see the value of companies helping consumers, but in the case of Hilton, we’re out. With its shares trailing the market in recent months, the stock trades at 33.3× forward P/E (or $323.84 per share). At this valuation, there’s a lot of good news priced in - we think there are better opportunities elsewhere. We’d recommend looking at a safe-and-steady industrials business benefiting from an upgrade cycle.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.