Since March 2026, Hubbell has been in a holding pattern, posting a small loss of 3.1% while floating around $457.27. The stock also fell short of the S&P 500’s 21.1% gain during that period.
Given the weaker price action, is now a good time to buy HUBB? Or should investors expect a bumpy road ahead? Find out in our full research report, it’s free.
Why Are We Positive on HUBB?
A respected player in the electrical segment, Hubbell (NYSE: HUBB) manufactures electronic products for the construction, industrial, utility, and telecommunications markets.
1. Long-Term Revenue Growth Shows Strong Momentum
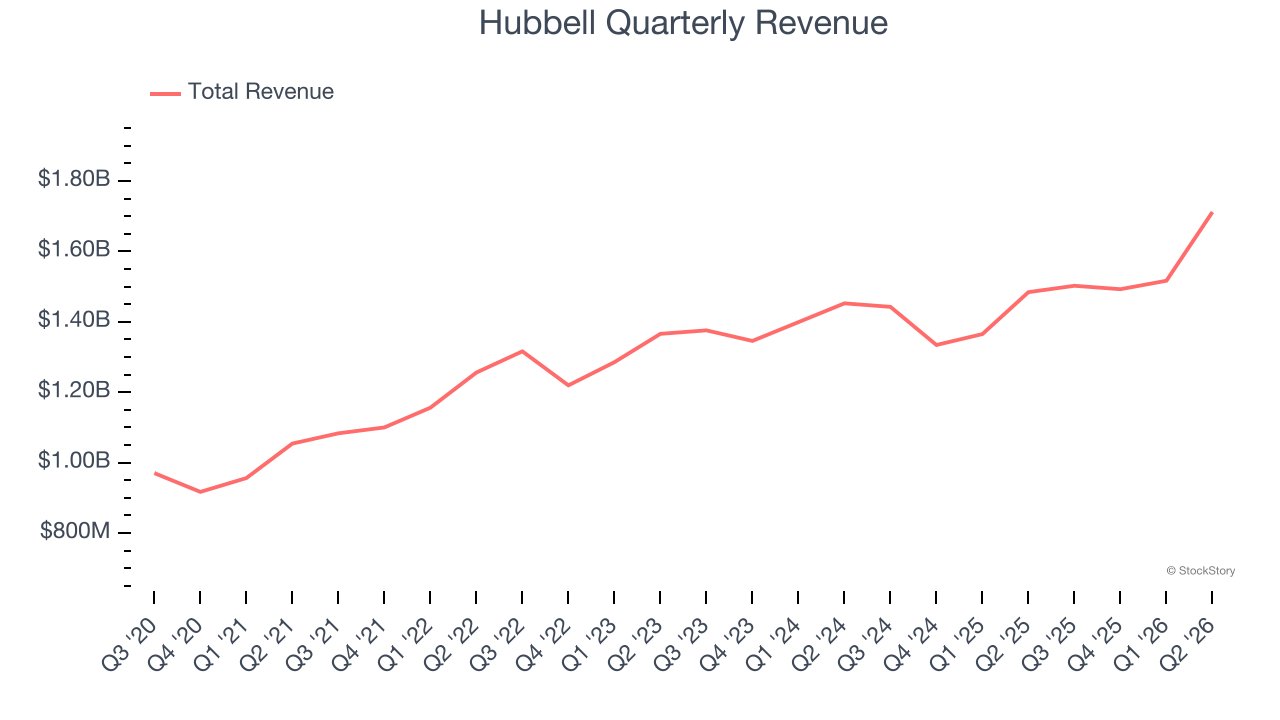
Examining a company’s long-term performance can provide clues about its quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Thankfully, Hubbell’s 9.8% annualized revenue growth over the last five years was solid. Its growth surpassed the average industrials company and shows its offerings resonate with customers.
2. Outstanding Long-Term EPS Growth
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
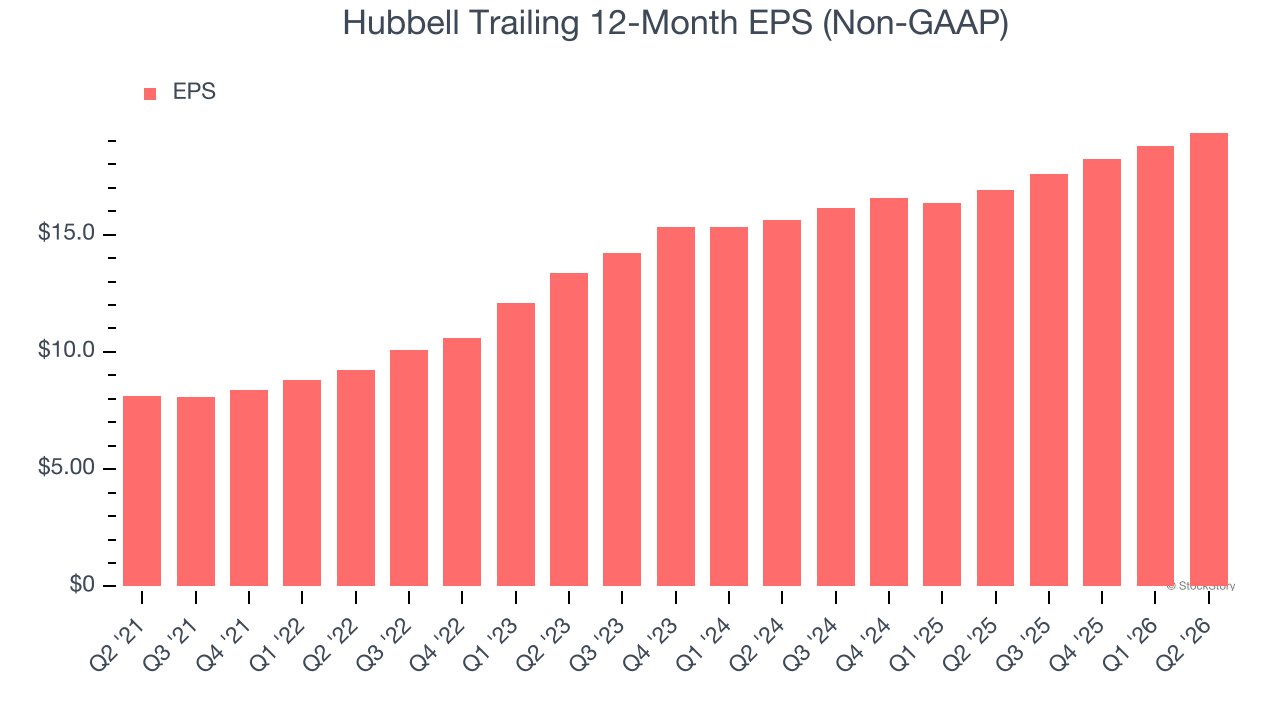
Hubbell’s EPS grew at 18.9% compounded annual growth rate over the last five years, higher than its 9.8% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
3. Increasing Free Cash Flow Margin Juices Financials
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
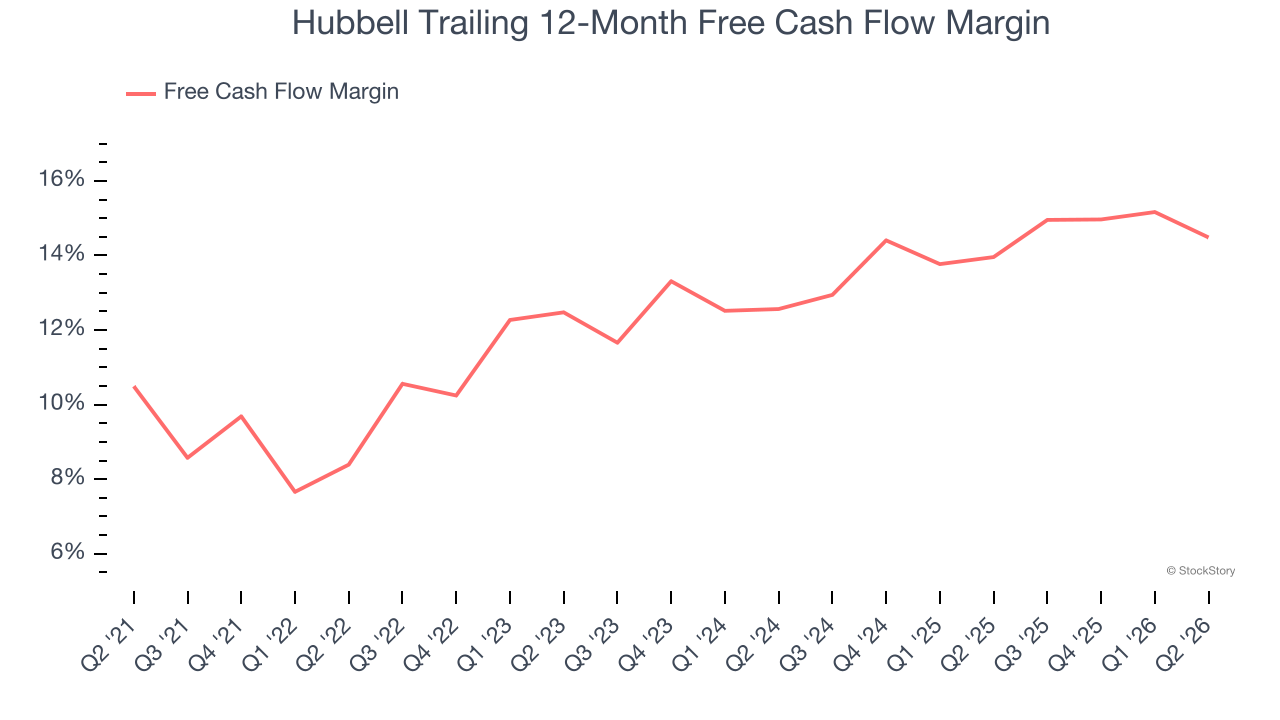
As you can see below, Hubbell’s margin expanded by 6.1 percentage points over the last five years. This is encouraging because it gives the company more optionality. Hubbell’s free cash flow margin for the trailing 12 months was 14.5%.
Final Judgment
These are just a few reasons Hubbell is a high-quality business worth owning. With its shares lagging the market recently, the stock trades at 21.4× forward P/E (or $457.27 per share). Is now a good time to initiate a position? See for yourself in our in-depth research report, it’s free.
Stocks We Like Even More Than Hubbell
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.