As the Q2 earnings season comes to a close, it’s time to take stock of this quarter’s best and worst performers in the ground transportation industry, including ArcBest (NASDAQ: ARCB) and its peers.
The growth of e-commerce and global trade continues to drive demand for shipping services, especially last-mile delivery, presenting opportunities for ground transportation companies. The industry continues to invest in data, analytics, and autonomous fleets to optimize efficiency and find the most cost-effective routes. Despite the essential services this industry provides, ground transportation companies are still at the whim of economic cycles. Consumer spending, for example, can greatly impact the demand for these companies’ offerings while fuel costs can influence profit margins.
The 15 ground transportation stocks we track reported a strong Q2. As a group, revenues beat analysts’ consensus estimates by 1.7%.
Amidst this news, share prices of the companies have had a rough stretch. On average, they are down 9.8% since the latest earnings results.
ArcBest (NASDAQ: ARCB)
Historically owning furniture, banking, and other subsidiaries, ArcBest (NASDAQ: ARCB) offers full-truckload, less-than-truckload, and intermodal deliveries of freight.
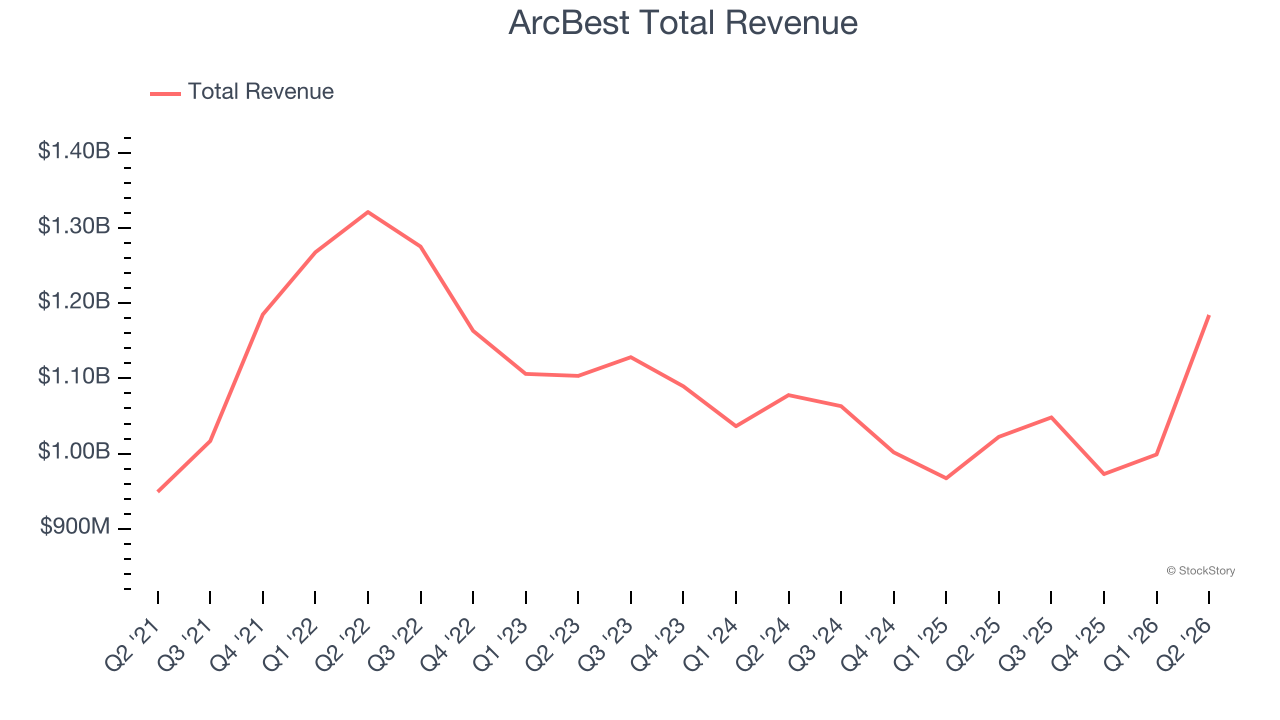
ArcBest reported revenues of $1.18 billion, up 15.9% year on year. This print was in line with analysts’ expectations, and overall, it was a strong quarter for the company with a decent beat of analysts’ EBITDA estimates and a beat of analysts’ EPS estimates.
“Our second-quarter performance reflects disciplined execution, a more constructive operating environment and the value customers are gaining from our integrated logistics solutions,” said Seth Runser, ArcBest President and CEO.
Investor expectations, however, were likely higher than Wall Street’s published projections, leaving some wishing for even better results (analysts’ consensus estimates are those published by big banks and advisory firms, not the investors who make buy and sell decisions). The stock is down 13.9% since reporting and currently trades at $128.77.
Is now the time to buy ArcBest? Access our full analysis of the earnings results here, it’s free.
Best Q2: RXO (NYSE: RXO)
With access to millions of trucks, RXO (NYSE: RXO) offers full-truckload, less-than-truckload, and last-mile deliveries.
RXO reported revenues of $1.77 billion, up 25% year on year, outperforming analysts’ expectations by 7.9%. The business had an incredible quarter with EBITDA guidance for next quarter exceeding analysts’ expectations and a beat of analysts’ EPS estimates.
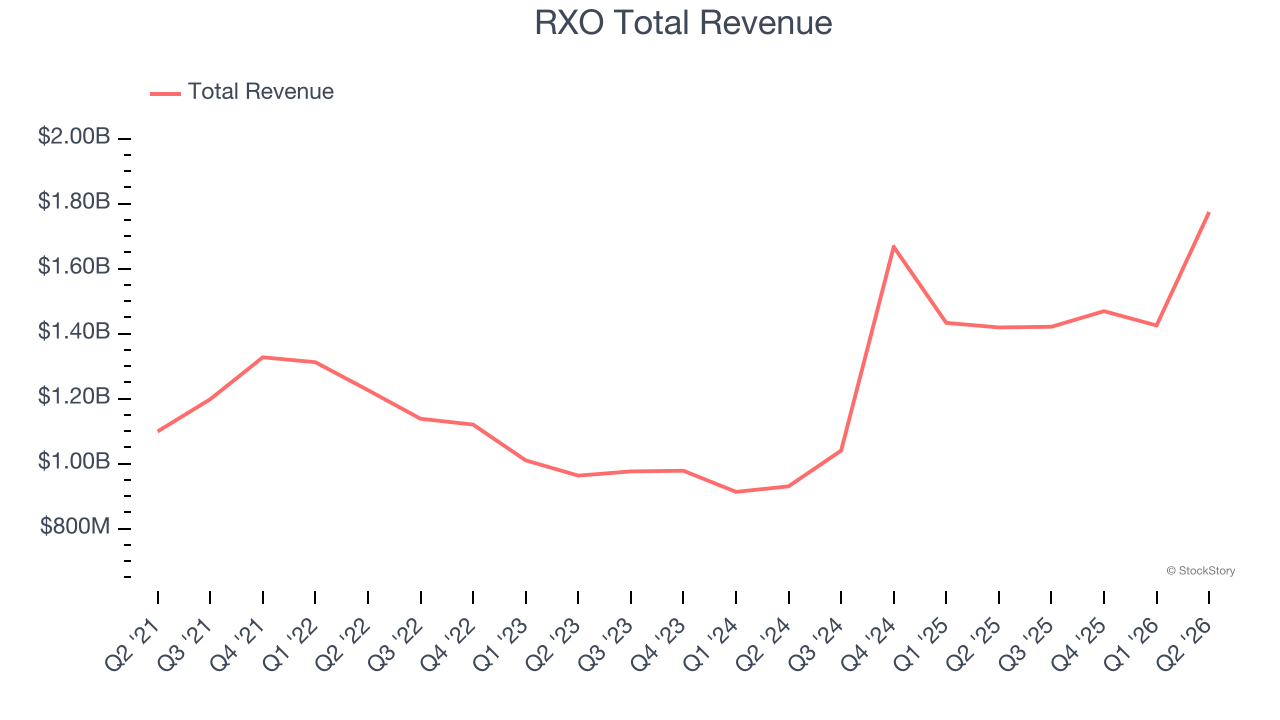
RXO scored the biggest analyst estimate beat and fastest revenue growth among its peers. However, the results were likely priced into the stock as it’s traded sideways since reporting. Shares currently sit at $21.05.
Is now the time to buy RXO? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: Werner (NASDAQ: WERN)
Conducting business in over a 100 countries, Werner (NASDAQ: WERN) offers full-truckload, less-than-truckload, and intermodal delivery services.
Werner reported revenues of $933.9 million, up 24% year on year, in line with analysts’ expectations. It was a slower quarter as it posted a significant miss of analysts’ EPS estimates and adjusted operating income in line with analysts’ estimates.
As expected, the stock is down 11.1% since the results and currently trades at $34.05.
Read our full analysis of Werner’s results here.
Ryder (NYSE: R)
As one of the first companies to introduce the idea of leasing trucks, Ryder (NYSE: R) provides rental vehicles to businesses and delivers packages directly to homes or businesses.
Ryder reported revenues of $3.35 billion, up 5% year on year. This number surpassed analysts’ expectations by 1.3%. Taking a step back, it was a mixed quarter as it also logged a narrow beat of analysts’ EPS estimates but EPS guidance for next quarter missing analysts’ expectations.
The stock is down 16.3% since reporting and currently trades at $231.23.
Read our full, actionable report on Ryder here, it’s free.
Knight-Swift Transportation (NYSE: KNX)
Covering 1.6 billion loaded miles in 2023 alone, Knight-Swift Transportation (NYSE: KNX) offers less-than-truckload and full truckload delivery services.
Knight-Swift Transportation reported revenues of $2.10 billion, up 12.6% year on year. This result topped analysts’ expectations by 2%. It was an exceptional quarter as it also logged a beat of analysts’ EPS estimates and EPS guidance for next quarter beating analysts’ expectations.
The stock is down 15.7% since reporting and currently trades at $64.12.
Read our full, actionable report on Knight-Swift Transportation here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Strong Momentum Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.