Over the last six months, AT&T’s shares have sunk to $26.05, producing a disappointing 6.1% loss - a stark contrast to the S&P 500’s 13.3% gain. This may have investors wondering how to approach the situation.
Is now the time to buy AT&T, or should you be careful about including it in your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Do We Think AT&T Will Underperform?
Even with the cheaper entry price, we don’t have much confidence in AT&T. Here are three reasons why there are better opportunities than T, plus one stock we’d rather own.
1. Long-Term Revenue Growth Flatter Than a Pancake
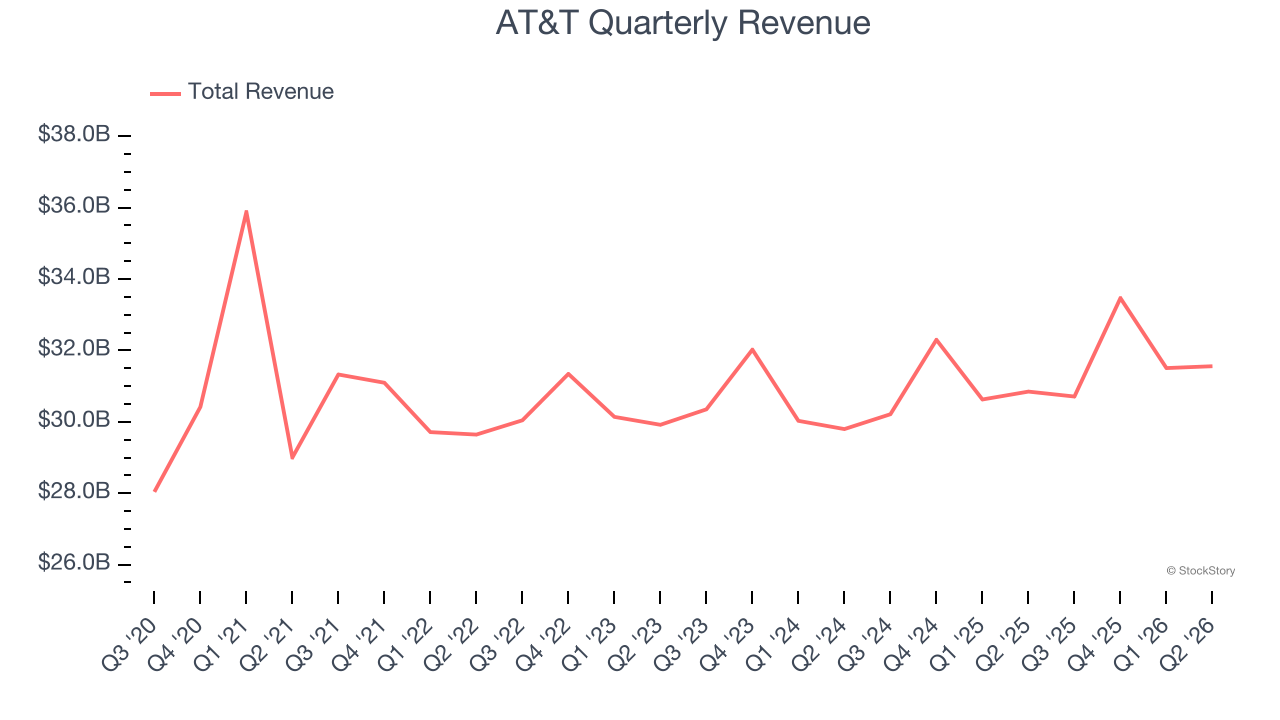
A company’s long-term sales performance is one signal of its overall quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Unfortunately, AT&T struggled to consistently increase demand as its $127.2 billion of sales for the trailing 12 months was close to its revenue five years ago. This was below our standards and signals it’s a low quality business.
2. EPS Trending Down
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
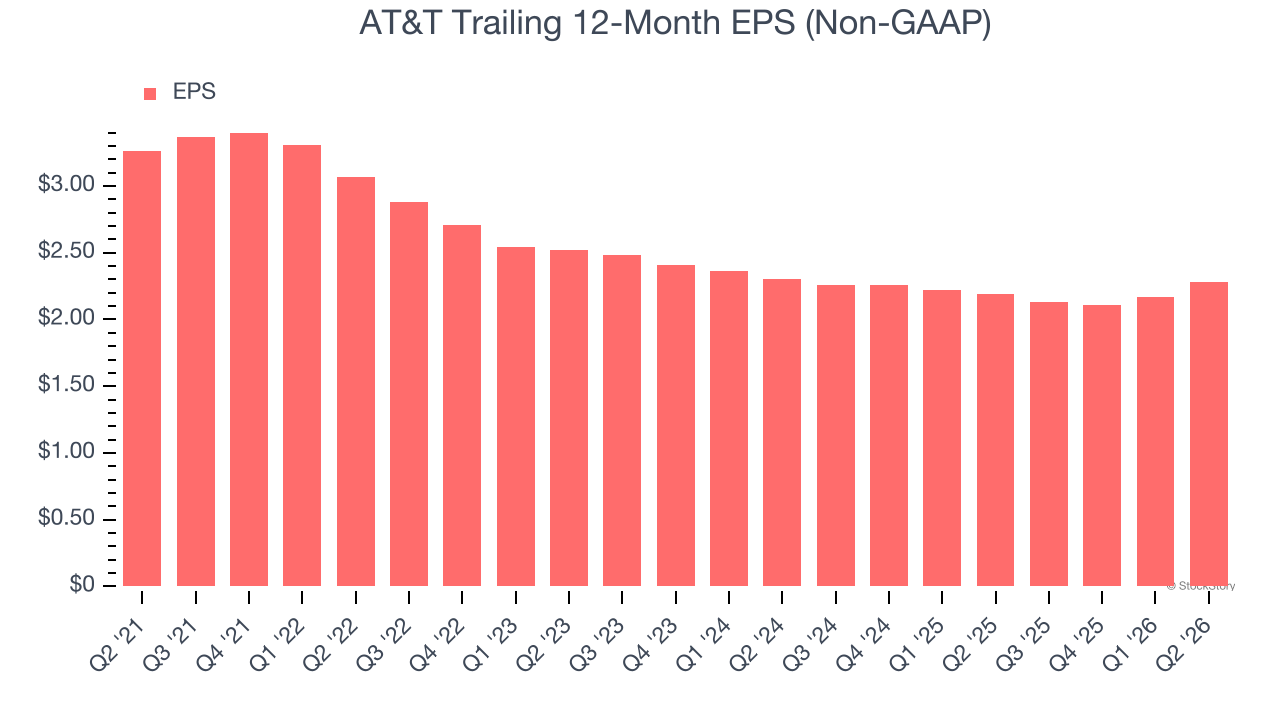
Sadly for AT&T, its EPS declined by 6.9% annually over the last five years while its revenue was flat. This tells us the company struggled because its fixed cost base made it difficult to adjust to choppy demand.
3. Free Cash Flow Projections Disappoint
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
Over the next year, analysts’ consensus estimates show they’re expecting AT&T’s free cash flow margin of 13.9% for the last 12 months to remain the same.
Final Judgment
AT&T doesn’t pass our quality test. After the recent drawdown, the stock trades at 10.6× forward P/E (or $26.05 per share). While this valuation is reasonable, we don’t see a big opportunity at the moment. There are superior stocks to buy right now. We’d recommend looking at one of our top digital advertising picks.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.